Nandivardhan Jain Noesis Capital Sees Hotel Boom Ahead
Nandivardhan Jain Noesis Capital, says India’s next hotel growth cycle will be driven by manufacturing and industrial expansion. Read the full analysis here.
 nishathapa
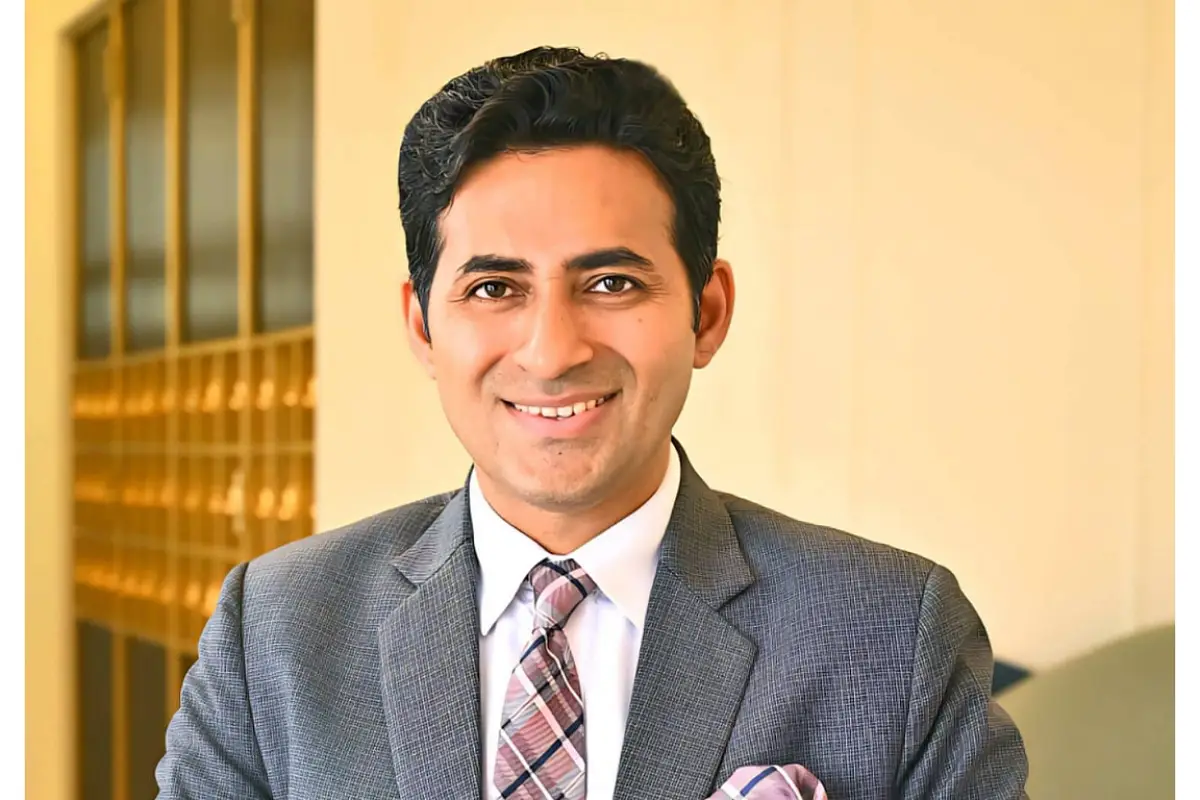
NEW DELHI, May 29, 2026: The conventional wisdom about where hotel investment opportunities lie in India has always started with tourism, leisure destinations, pilgrimage towns, metro markets, and gateway commercial cities. Nandivardhan Jain, Founder and CEO of Noesis Capital Advisors, argues that this framework is no longer the complete picture and that the most significant new source of hotel demand emerging in India is not the holidaymaker, but the engineer, the EPC contractor, the defence supplier and the logistics operator who have nowhere credible to stay when they arrive for work.
The argument is grounded in a specific economic thesis: India is entering a manufacturing supercycle, driven by the global rewiring of supply chains away from China and by India's own domestic push for self-reliance across defence, energy, electronics and infrastructure. Those two forces together are redirecting industrial investment at a scale and pace that is generating real, durable hotel demand in markets that hospitality investors have historically overlooked. The question Jain is posing is not whether that demand will materialise. It is whether investors will position capital ahead of it or chase it after it is already priced in.
The Global Supply Chain Reset Is Driving Capital Into India's Industrial Corridors
The foundation of Jain's analysis is the structural shift in global manufacturing strategy that followed the compounding shocks of the past six years, the pandemic, the semiconductor shortage, the war in Ukraine and ongoing US-China trade tension. Companies and governments that once prioritised cost efficiency in their supply chains are now prioritising resilience and risk distribution. The result is a large-scale redistribution of manufacturing investment away from China and toward markets that combine scale, engineering talent, domestic consumption and political stability.
India, Jain argues, sits at the centre of this redistribution as one of very few countries that can genuinely absorb the investment at the scale it is being deployed. The China Plus One strategy, where companies maintain Chinese manufacturing but add a second base elsewhere, and the more aggressive China Negative One approach, where capacity is moved out of China entirely, are both pointing toward India as the primary beneficiary. This is not a passing trend, in Jain's assessment. It is a structural reorientation of global industrial capital that will continue for the next twenty years.
India's Homegrown Self-Reliance Push Compounds the Opportunity
Running alongside the global supply chain reset is a domestic policy agenda that Jain describes as a genuine commitment to self-reliance rather than a political slogan. India is pushing to build its own capability in defence, energy, electronics, aerospace, semiconductors and renewable systems, sectors where dependence on imports has historically represented strategic vulnerability. When a country makes that commitment at scale, the same chain reaction follows every time: industrial corridors are built, manufacturing capacity expands, logistics networks and supplier ecosystems grow up around them, and every layer of that ecosystem eventually needs accommodation for the people running it.
India's defence production crossing Rs 1.5 lakh crore is the single most powerful example of what this creates for hospitality. Defence manufacturing generates a specific and highly durable type of hotel demand, engineers, government officials, foreign partners, procurement teams and defence contractors who travel on recurring schedules, stay for extended periods and are relatively insulated from the economic volatility that disrupts leisure demand. The same pattern holds for renewable energy corridors, semiconductor parks, data centre clusters and the logistics networks that tie them together.
The Numbers Behind India's Structured Supply Gap
Jain's argument gains its sharpest edge from the supply-demand data for India's hotel sector. According to Noesis Capital research, India currently has approximately 375,000 branded and organised hotel rooms. Projected demand by 2030 approaches 630,000 rooms. That gap of more than 250,000 rooms is one of the largest supply deficits relative to demand among major economies globally, a structural tailwind that would be commercially significant even if demand were growing only modestly.
But demand is not growing modestly. It is growing from multiple directions simultaneously: the established leisure, metro and commercial segments continuing to expand, and the entirely new industrial demand layer being added on top. The supply gap that already existed is being widened by a demand source that most of the hospitality investment community has not yet priced into its underwriting models.
The New Map of Indian Hotel Investment Includes Cities That Were Not on the Old One
The practical implication of Jain's thesis is a redrawing of the hotel investment map. The established markets, Mumbai, Delhi, Goa, Jaipur, Bengaluru, remain anchor positions in any serious portfolio. But the map is growing, and the growth is happening in cities that feature rarely in hotel investment conversations: Aurangabad, Nashik, Nagpur, Lucknow, Kanpur, Hosur, Bhubaneswar, Coimbatore, Vizag, Vadodara, Surat. These cities are becoming industrial ecosystems in their own right, and many of them remain structurally underpenetrated from a branded hotel supply perspective. Land is still affordable. Competition is thin. Branded supply is scarce. That combination, against a backdrop of rising industrial demand, is where Jain argues long-term value is currently hiding in plain sight.
The global precedent is consistent and well-documented. Huntsville, Alabama, became a sustained business hospitality market on the back of aerospace and defence investment. Jubail in Saudi Arabia generated durable hotel demand from petrochemical and energy infrastructure. Suzhou in China built a full urban hospitality economy on top of an industrial park foundation. In each case, investors who entered early captured both rising demand and rising land value. Investors who waited for the demand to become obvious to everyone found they had waited too long.
Timing Is the Central Constraint in Industrial Hospitality Investment
Jain is direct about why the timing of this analysis matters. A hotel is a five-to-six-year project from land acquisition to stabilisation. By the time industrial demand in a given corridor becomes self-evident to the market, land prices have risen, competition has crowded in, construction costs have climbed, and the margins that justified the original investment have compressed. The window where the opportunity is genuine but not yet priced is open now, in Jain's assessment, because the industrial investment flows are visible and directionally clear while the hotel supply response has not yet followed them into the relevant markets.
The caveat he attaches to this is important: industrial hospitality markets reward discipline at entry more than almost any other segment, because the demand is real but the room for mistakes is small. Picking the wrong corridor, the wrong product type or the wrong brand structure can turn a structural tailwind into a stranded asset. The difference between a hotel that compounds value across decades and one that bleeds cash traces back to three decisions made at the very beginning, rigorous feasibility, the right brand alignment and a sensible debt structure.
What Jain is ultimately arguing, through the lens of Noesis Capital Advisors' research and the global industrial hospitality playbook, is that the largest hospitality investment opportunity of the next decade is not in the obvious cities. It is in the cities that are about to become obvious, the manufacturing corridors, industrial hubs, energy ecosystems and defence manufacturing clusters where India's economic transformation is actually being built, and where quality hotel accommodation remains one of the most significant items of missing infrastructure.