Asia Hotel Market Shifts as Accor Pushes Conversions and Mid-Scale Growth
The Asia hotel market is shifting as Accor prioritizes conversions and mid-scale growth. Explore how franchise models drive 2026 hospitality trends.
 Punita Thakur
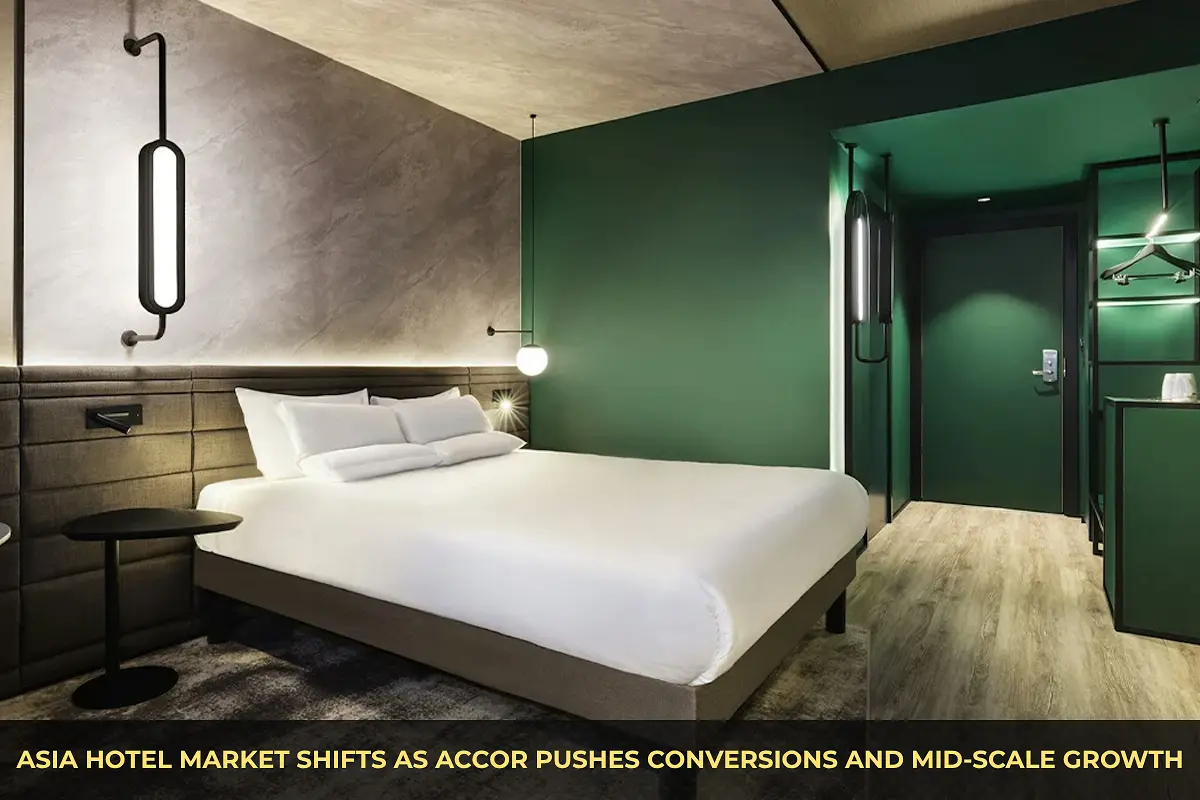
The Asia hotel market is undergoing structural changes in 2026 as Accor accelerates property conversions and expands its mid-scale portfolio, responding to shifting traveler preferences and rising competition, the company’s Chief Development Officer Andrew Langdon said at the Skift Asia Forum. This surge in hotel conversions Asia wide is allowing for faster market entry.
The Accor expansion marks a move away from traditional new-build developments toward repositioning existing properties, allowing faster market entry and lower capital risk. The shift comes as mid-scale and economy hotels emerge as the fastest-growing segments across the region.
Asia Hotel Market Shifts Toward Property Conversions Gains Momentum
Hotel conversions are becoming a central growth strategy for operators across Asia. Instead of building new assets, brands are acquiring or leasing existing properties and rebranding them to align with evolving market demand.
The rapid midscale hotels growth is attracting a new wave of investors. Accor indicated that conversion activity is increasing year-on-year, reflecting broader industry adoption of capital-efficient expansion models.
The approach also allows brands to quickly reposition properties across segments. For example, assets originally positioned as luxury hotels can be rebranded into premium mid-scale offerings to target higher occupancy and broader customer bases.
Mid-Scale and Economy Segments Drive Expansion
Market data shows that mid-scale and economy hotels are leading growth in Asia’s hospitality sector in 2026. These categories are attracting investment due to consistent returns and alignment with demand from middle-income travelers and business segments.
Mid-scale hotels are positioned between affordability and service quality, offering modern amenities, contemporary design, and competitive pricing. Economy hotels, meanwhile, are gaining traction among digitally focused travelers who prioritize convenience and value over luxury features.
Accor’s portfolio strategy reflects this shift, with a majority of its regional expansion focused on these segments. The company is also targeting secondary and tertiary cities, where around 60% of new investments are being directed.
Franchise Model Becomes Primary Growth Engine
Franchising has emerged as the dominant model for expansion, accounting for approximately 70% of properties in Asia’s hotel market. This model allows global brands to scale rapidly while reducing ownership costs and leveraging local operator expertise.
Under franchise agreements, local partners manage property development and operations, while international brands provide systems, branding, and distribution networks. This structure is particularly effective in diverse markets where local knowledge is critical for performance.
Accor’s ability to combine franchise partnerships with flexible brand conversion strategies provides a competitive advantage, enabling faster repositioning and market adaptation compared to single-brand operators.
Generational Trends Reshape Demand Patterns
Changing consumer behavior, particularly among younger travelers, is a key driver behind the sector’s transformation. These travelers prioritize digital integration, seamless connectivity, and value-based experiences over traditional luxury attributes.
As a result, older hotel properties without modern amenities are increasingly being upgraded or rebranded. Conversion projects typically include improvements in technology infrastructure, design, and sustainability features to meet current expectations.
This shift is also influencing product design, with hotels focusing more on functionality, local experiences, and operational efficiency rather than large-scale luxury investments.
Implications for Investors and Operators
The evolving market dynamics are creating new opportunities for investors, particularly in acquiring underperforming assets and repositioning them through brand conversions. Lower acquisition costs combined with improved operational models are driving interest in this strategy.
Secondary markets are also gaining prominence, offering higher growth potential compared to saturated metropolitan areas. Improved infrastructure and rising domestic travel demand are supporting expansion in these regions.
At the same time, operators are under pressure to invest in digital systems and sustainability initiatives, which are increasingly influencing both customer choice and brand partnerships.
For travelers, the transformation is resulting in improved service standards, expanded choices across price segments, and better integration of local experiences within global hotel brands.