Dubai Hotel Bookings Rise as Gulf Carriers Restore Flights
Dubai hotel bookings are climbing as Gulf carriers restore long-haul capacity, with occupancy expected to reach up to 66 percent by year end after a difficult H1 2026.
 RUKAIYA KADIWAL
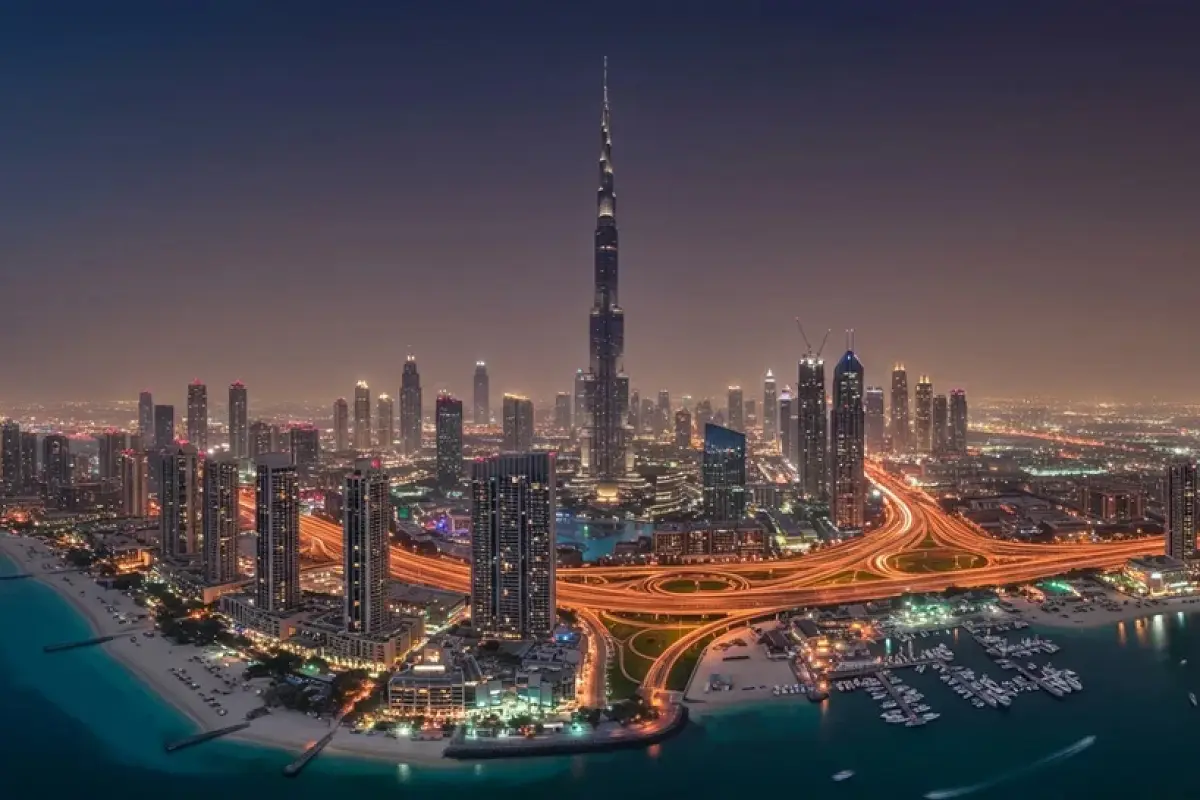
Dubai hotel bookings are rising again, and the people rebuilding them are not waiting for a formal signal to begin. Front office staff are being rehired. Housekeeping teams are being expanded. Food and beverage operations are scaling back up across properties that spent the first half of 2026 running at occupancy rates far below what Dubai's hotel infrastructure was designed to absorb. The recovery is underway, but it is moving on different schedules across different segments of the market, and the winter season ahead will determine how much of 2025's record performance the city can recover.
The disruption that produced this recovery was not a demand collapse in the conventional sense. Regional conflict disrupted airspace, forced airlines to cancel and reroute flights, and weakened the international connectivity that feeds every hotel, attraction, restaurant, and retail outlet in the city. Dubai did not become less appealing as a destination. It became harder to reach. That distinction shapes how the recovery is being managed and what needs to happen before it can be considered complete.
What the Numbers Show About Dubai Hotel Bookings in H1 2026
The Dubai Hospitality Market Performance H1 2026 report from Cavendish Maxwell, drawing on STR and Data.Dubai figures, puts average hotel occupancy at 56.4% in the first half of the year, while average daily rate fell 7 percent to AED701. Those figures represent a sharp departure from 2025, when Dubai welcomed a record 19.59 million international overnight visitors, hotel occupancy reached 80.7 percent, and occupied room nights rose 4 percent to 44.85 million.
Cavendish Maxwell now expects Dubai hotel occupancy to reach between 60.4 and 66.2 percent by the end of 2026, with ADR in the AED600 to AED675 range. Those figures would mark a meaningful improvement from the first half but would still leave the market some distance from 2025's extraordinary performance, a gap that matters differently to hotel operators managing daily room counts than it does to owners and investors watching ADR, RevPAR, and margins.
Gulf Carriers and the Speed of Air Capacity Restoration
Emirates has restored approximately 85 percent of its pre-conflict capacity, with further additions expected as the year progresses. Emirates President Tim Clark said the airline was operating close to full capacity, while Dubai Airports chief executive Paul Griffiths pointed to improving conditions at the hub. Those are encouraging signals from the carriers that can put the most capacity back into the Dubai market quickly.
The more cautious group is overseas airlines, which have been slower to restore services as they continue to assess geopolitical risk. For Dubai, that difference matters considerably. Emirates and flydubai can restore domestic Gulf and regional connectivity rapidly, but the city's tourism economy depends on the breadth of foreign airline networks feeding travelers from Europe, Asia, Africa, and the Americas. Every restored long-haul frequency puts potential guests back into the hotel pipeline. It also supports tour operators, destination management companies, airport retailers, attractions, and the meetings and events sector.
A Shorter Booking Window and What It Means for Hotels
The returning demand is not behaving exactly as it did before the disruption. Hotels have reported improving reservations ahead of the peak winter period, but booking windows have shortened considerably. TUI, Europe's largest tour operator, reported that booked revenue had risen 7 percent over the four weeks to August 12, with chief executive Sebastian Ebel noting that customers were still traveling but increasingly booking closer to departure.
That shift complicates revenue management for Dubai hotels in a specific way. Forward bookings in August and September may look softer than operators would like, only for demand to arrive much closer to the actual winter travel date. For revenue managers, the temptation to discount early in response to soft forward demand could prove costly if late demand materializes at the scale the recovery signals suggest it might. Managing that tension between current visibility and expected late bookings is one of the more consequential operational challenges the industry faces heading into the fourth quarter.
A More Diversified Source Market Provides Resilience
Dubai enters this recovery with a visitor economy that is more geographically spread than it was during earlier regional crises. Western Europe accounted for about 21 percent of visitors entering 2026, while the CIS and Eastern Europe, GCC, and South Asia each contributed around 15 percent, according to CBRE's UAE Real Estate Market Review. That spread gives tourism authorities, airlines, and hotel groups the flexibility to respond as confidence recovers at different speeds in different markets.
Hotels have already reported improving booking trends from the UK, Russia, and CIS markets, with demand expected to strengthen as the events and festive calendars gather pace. The easing of travel warnings has helped British travelers in particular, who faced not only regional security concerns but practical questions around insurance and flight disruption during the most difficult months. Removing those obstacles does not produce an immediate surge, but it reopens the booking pipeline. The UK remains particularly important for winter leisure demand, while India supports a mix of leisure, business, and visiting-friends-and-relatives traffic.
Mid-Market Hotels and the Wisdom of Diverse Inventory
One of the more revealing findings in the Cavendish Maxwell data is the relative resilience of Dubai's mid-market hotel segment during the downturn. Years of hotel development have expanded the city's accommodation inventory across upscale, lifestyle, mid-market, serviced apartment, and more affordable categories. That diversity matters for recovery because it allows different segments of returning demand to be absorbed without forcing luxury hotels to chase occupancy through heavy rate discounting that could linger long after the crisis has passed.
JLL's analysis of the UAE hospitality market found that operators responded to softer international demand with competitive pricing and staycation offers, while some used the quieter period to accelerate refurbishment programmes. That kind of productive use of lower occupancy periods reflects operational maturity. Properties that emerge from a downturn with freshly upgraded rooms and refreshed food and beverage offerings are better positioned to capture returning guests than those that simply waited for conditions to improve.
What Dubai's Recovery Reveals About Modern Tourism
Dubai's hospitality sector has recovered from external shocks before, but the scale of its tourism economy is now considerably larger. More hotel rooms, more airline capacity, and a wider international source market create resilience. They also magnify the consequences when air connectivity breaks down, because the fixed cost base of a 19 million visitor economy does not compress easily when flight schedules collapse.
The same underlying truth applies across hospitality markets at very different scales. A chef choosing where to open a restaurant weighs air connectivity, foot traffic, and demand confidence in ways that are structurally similar to how Dubai's tourism planners are thinking about the winter season. Coverage of what drives a Michelin-starred chef's decision to open in downtown San Jose reflects that same logic at a smaller scale, where market confidence and accessible demand determine whether a new hospitality investment makes sense right now or not yet.
What the Winter Season Will Tell the Industry
Dubai's strongest international leisure period traditionally runs from October into the first quarter. If restored airline capacity converts into occupied rooms, late-booking European demand holds, and the winter events calendar delivers its usual lift, the city could enter 2027 with the worst of the tourism shock behind it. None of that is guaranteed. Foreign airlines may restore capacity more slowly than Gulf carriers, geopolitical uncertainty has not disappeared, and a strong fourth quarter will not erase the weak first-half numbers.
For the hotel front office staff being hired back into their roles this month, the winter season will feel different from any other year. They know why the rooms were empty in the spring. They know who refilled the calendar, and they understand, more clearly than any industry report can capture, what it means to work in a city whose hospitality economy runs on confidence that air travel has returned.
Learn more at Travel Daily Media's official website.