India Hotel Sector Growth Builds Momentum Into H2 FY27
India hotel sector growth accelerates into H2 FY27, with leisure destinations outperforming city hotels and RevPAR rising 11 to 13 percent despite global disruptions.
 RUKAIYA KADIWAL
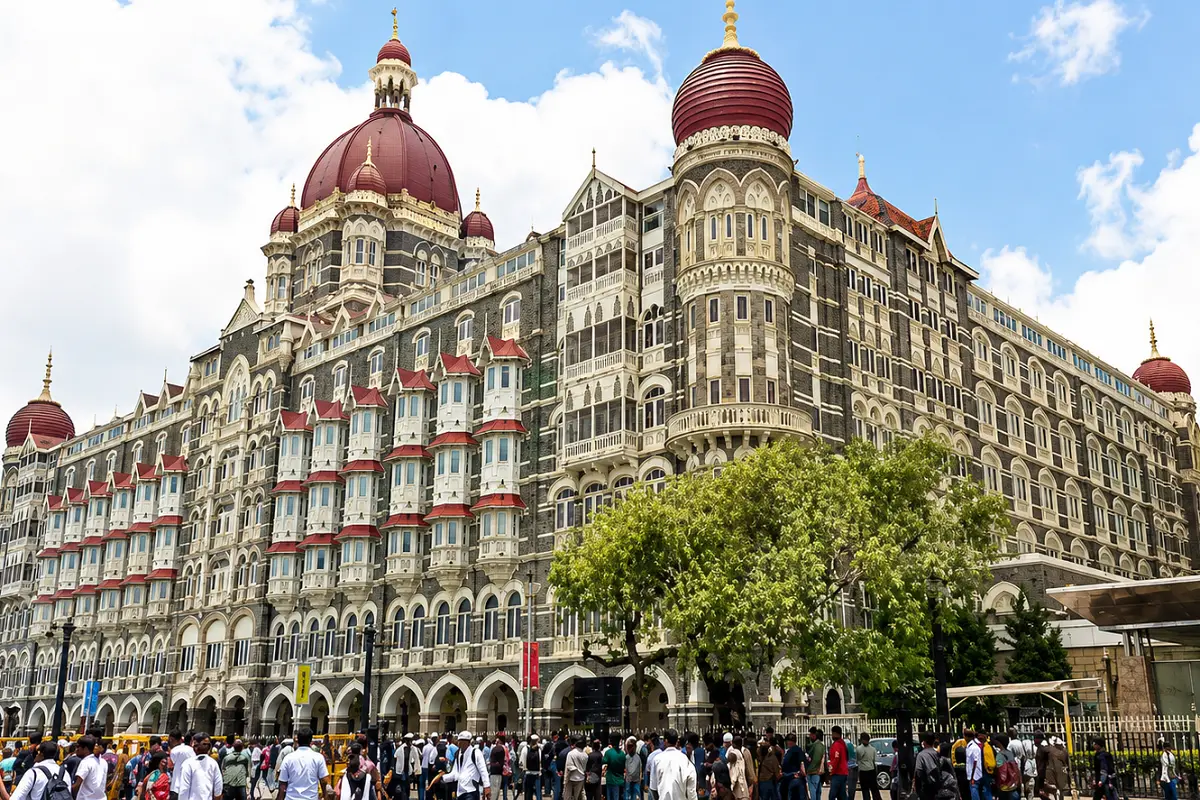
In Rajasthan, the hotels fill up before the wedding season officially arrives. Families begin calling months in advance, not for rooms alone but for entire wings, for courtyard spaces, for the kind of accommodation that can hold a celebration large enough to justify the distance traveled to reach it. In Goa, resort bookings track a rhythm defined by domestic travelers who have, in recent years, shown a consistent willingness to spend more per night than the market previously assumed they would. These are not abstract trends. They are the daily reality of an Indian hospitality sector that is performing better than its headline disruptions might suggest.
India Hotel Sector Growth Signals a Stronger Second Half
A PhillipCapital sector report released in August 2026 confirmed what hotel operators across India's leisure destinations had already been experiencing on the ground. India hotel sector growth is expected to strengthen in the second half of FY27, supported by robust domestic leisure demand, a heavier wedding calendar in the coming months, recovering MICE activity, and a seasonal uptick in international travel from October onward.
The first quarter of FY27 set a solid foundation for that outlook. Despite geopolitical disruptions that affected international traffic and kept corporate travel budgets cautious, industry occupancy rose by two to four percentage points year-on-year. Average room rates increased six to eight percent, and revenue per available room grew eleven to thirteen percent. Those figures represent meaningful performance in a quarter that historically carries softer demand and that played out against an external environment more complicated than most operators would have chosen.
Leisure Destinations Leading the Recovery
The divergence between leisure and business hotel performance in Q1FY27 was among the quarter's most defining characteristics. Rajasthan and Goa, two of India's most established leisure markets, recorded high-twenty-percent RevPAR growth for Indian Hotels during the period. Chalet Hotels' resort properties posted nineteen percent RevPAR growth, compared with around five percent for its business hotels. Leela Hotels' resorts recorded twenty-four percent RevPAR growth against fourteen percent for its city properties.
That gap between resort and urban hotel performance tells a story about where Indian domestic travel demand is currently concentrated. Leisure travel, driven by weddings, family holidays, and the continuing shift of destination celebrations to properties within India rather than abroad, has sustained a level of spending that business travel has not yet matched. The PhillipCapital report noted that all-destination weddings and celebrations increasingly remaining within India has become a structural support for leisure hotel demand, one that operates somewhat independently of the geopolitical and corporate travel variables affecting other segments.
What the Numbers Behind Corporate Travel Show
Corporate travel remained the quarter's softer story. Geopolitical uncertainty and tighter travel budgets among companies meant that business hotels did not benefit from the same demand momentum that leisure properties experienced. International traffic was further affected by disruptions linked to the West Asia conflict, with international passenger numbers declining around ten percent year-on-year to 17.9 million in Q1FY27. Domestic air passenger traffic grew just 1.2 percent year-on-year to 86.3 million over the same period.
Those top-line figures, however, obscure a monthly trend that moved in a more encouraging direction as the quarter progressed. Domestic passenger growth rose 7.7 percent in May before moderating. The decline in international traffic narrowed significantly, from 18.3 percent in February to 4.7 percent in June, a trajectory that supports the PhillipCapital view that the second half of the fiscal year carries a more positive demand environment than the first quarter suggested at its opening.
How Individual Hotel Companies Performed
Across the companies covered in the PhillipCapital analysis, the revenue picture was broadly positive despite the mixed demand environment. Leela Hotels reported twenty-eight percent revenue growth and forty-one percent EBITDA growth in Q1FY27, a performance driven heavily by its resort properties' strong RevPAR expansion. Indian Hotels' revenue rose fifteen percent with EBITDA growth of eighteen percent, while ITC Hotels recorded eight percent RevPAR growth. Lemon Tree's occupancy improved by 314 basis points over the same period.
The report noted that industry pricing remained intact even in markets where occupancy softened, an important signal about the structural health of the sector. A hotel industry that maintains rate discipline during a soft occupancy quarter is one that has built enough genuine demand to resist the temptation to discount its way to higher room counts. That pricing resilience suggests operators are managing their inventory with more confidence than in previous cycles.
What Could Strengthen the Outlook Further
The PhillipCapital report identified limited new hotel supply in key markets as a factor likely to support room rates and RevPAR as demand improves. When supply growth is constrained, the pricing power of existing properties increases, particularly in markets where leisure demand is as concentrated and consistent as it has become in Rajasthan and Goa. That supply constraint, combined with a heavier wedding calendar and improving international connectivity from October onward, forms the basis for the sector's more optimistic H2FY27 projection.
The report's language on the demand outlook was measured rather than bullish. "Demand outlook remains positive for Q2FY27, with domestic leisure demand staying strong, corporate travel gradually normalising, and international demand recovering, as connectivity improves," it said. The sequencing matters. Domestic leisure leads. Corporate travel follows. International travel recovers as the infrastructure disruptions ease. Each layer adds to a demand picture that improves across the year rather than arriving all at once.
Supply Discipline and Its Consequences
The relative scarcity of new hotel supply entering key Indian markets in this period is not simply good news for existing operators. It reflects a development environment in which construction costs, financing conditions, and regulatory timelines have made new hotel projects more difficult to bring to market than demand trends alone would suggest. For travelers, constrained supply means fewer options in the markets they most want to visit, which translates to higher rates and, at peak periods, genuine difficulty securing preferred properties.
For the hotel industry, that same constraint supports the investment case for existing assets and for the operators capable of extracting maximum performance from properties already in the market. The companies that have built strong resort portfolios in Rajasthan, Goa, and Kerala are positioned to benefit from a demand environment that is growing faster than the supply entering those markets.
An Industry Reading Its Own Momentum
India's hotel sector enters the second half of FY27 with a set of conditions that, taken together, point toward continued improvement. Domestic leisure demand has demonstrated a resilience that held through geopolitical disruption and seasonal softness. Corporate travel is normalising gradually. International traffic, having fallen sharply earlier in the year, is recovering month by month. The wedding calendar is full. MICE activity is returning. Supply in key markets remains limited. None of these conditions guarantee a particular outcome, but together they describe an industry that has absorbed a difficult first quarter and arrived at the second half with its pricing intact, its occupancy improving, and its demand drivers largely aligned. In a sector as sensitive to external conditions as hospitality, that kind of accumulated resilience is worth noting carefully, and perhaps more carefully than the headline numbers alone would suggest.
Related reading: Global Hotel Alliance adds Turkish and Polish brands