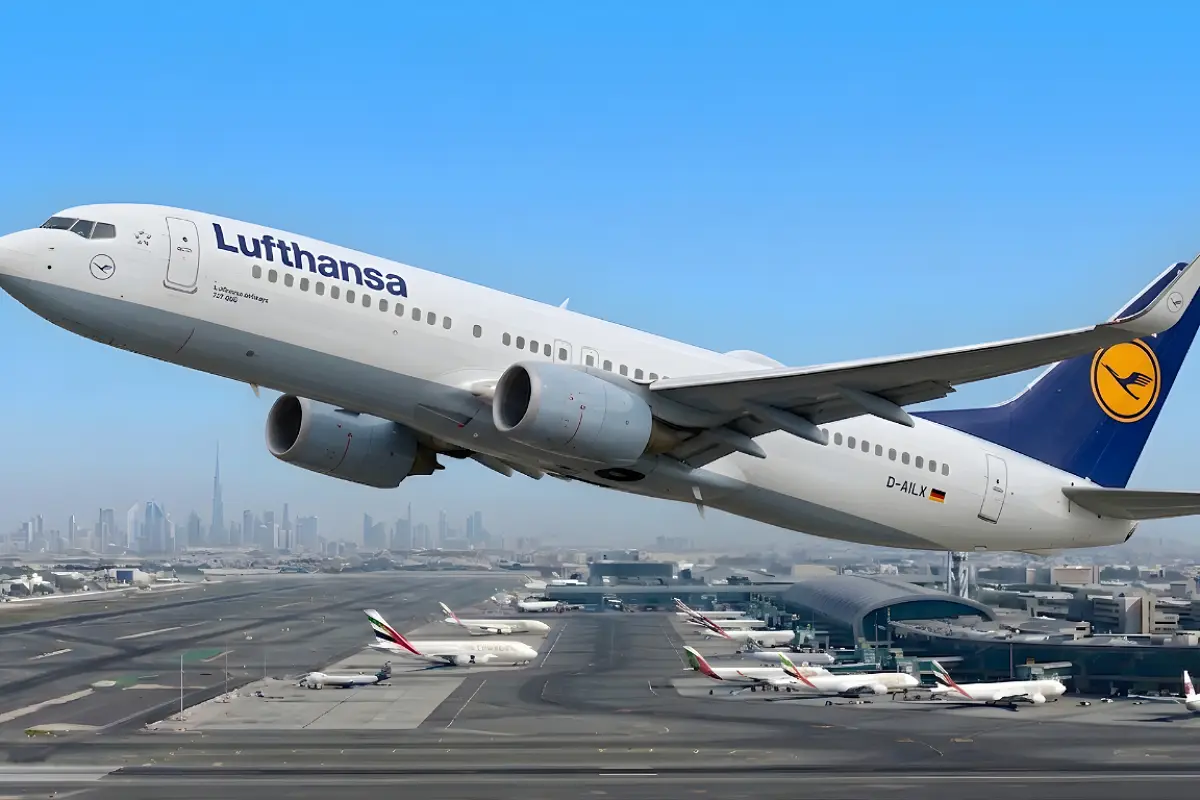
Lufthansa Eyes Bold Eurobond Move as Aviation Costs Escalate
Lufthansa Eurobond funding plan aims to boost liquidity amid rising fuel costs, delivery delays, and geopolitical uncertainty in 2026.
 Jishan Khan
Lufthansa Is Going Back to the Bond Market, And That Should Tell You Something
Strong passenger demand is not enough anymore. Europe's biggest airline group is building a financial cushion, and the reasons why matter for every carrier watching from the sidelines.
When a profitable airline starts raising fresh debt, most people assume something is wrong. With Lufthansa, the reality is more strategic than that, and more telling about where European aviation is actually headed in late 2026.
The German carrier is reportedly in talks to issue Eurobonds, a move designed to shore up liquidity at a time when fuel costs are climbing, aircraft deliveries keep getting pushed back, and geopolitical tension across Europe and the Middle East is making long-term planning genuinely difficult. This is not a distress signal. It is Lufthansa doing what large, well-run companies do when they see turbulence coming before it arrives.
Why a Profitable Airline Still Needs Fresh Capital
This is the part that confuses most people outside the industry. Lufthansa is not bleeding money. Travel demand across Europe remains strong. Seats are filling up. So why raise debt now?
Because profitability and liquidity are two completely different things in aviation.
An airline can be reporting solid earnings while simultaneously sitting on a fleet modernization bill worth billions, a debt refinancing deadline that cannot be pushed, and a fuel hedging position that gets more expensive every quarter oil prices move the wrong way.
In simple terms, Lufthansa is not borrowing because it is struggling. It is borrowing because it wants to make sure a bad quarter two years from now does not turn into a crisis.
The Aircraft Delivery Delays Problem Is Forcing Every Major Carrier to Rethink Finances
One of the clearest drivers behind this bond issuance is something every major European carrier is dealing with right now, delayed aircraft deliveries from both Boeing and Airbus are forcing airlines to keep older, less fuel-efficient jets in service longer than planned.
That costs more to operate. It costs more to maintain. And it pushes fleet modernization spending further into the future without actually reducing it.
So Lufthansa is essentially financing a problem it did not create, caused by manufacturers it has been waiting on for years. The Eurobond is partly how it manages that gap without letting it quietly erode the balance sheet.
What Geopolitical Uncertainty Is Actually Doing to Airline Planning
The Middle East situation and ongoing European instability are doing something specific to airline economics that does not always get explained clearly, they are making it nearly impossible to forecast revenue with any confidence beyond two or three quarters.
When you cannot confidently predict how many of your long-haul routes will be disrupted, which overflight corridors will remain open, or what jet fuel will cost when oil markets react to the next escalation, you stop relying on operating cash flow alone to cover major financial commitments.
You build a buffer. That is exactly what the Eurobond issuance is.
This Is Not Just a Lufthansa Story
What makes this development genuinely significant is that Lufthansa is not a carrier on the edge. It is one of the strongest, most diversified airline groups in Europe. If even Lufthansa is turning back to capital markets to prepare for potential slowdown, it tells you something important about what the rest of the industry is quietly thinking.
The carriers without Lufthansa's credit rating, without its route diversity, without its loyalty program revenue, they are watching this move and wondering whether they waited too long to do the same thing.
What It Means for Passengers
For now, nothing dramatic changes at the airport. But if Lufthansa uses this capital to accelerate fleet upgrades, passengers on long-haul routes stand to benefit from newer aircraft, better fuel efficiency, and potentially more competitive pricing as the cost structure improves.
The bigger risk is if the economic slowdown analysts are warning about actually arrives. In that scenario, the airlines that built financial buffers early will survive it. The ones that did not will be making the kind of headlines that involve restructuring advisors and sale banners, much like what we are already seeing with Norse Atlantic.
Lufthansa is making sure it is not in that second group.