APAC Hotel Investment 2026: Vietnam, India Lead Growth, Says CBRE
APAC hotel investment 2026 sees Vietnam and India lead, driven by rising room rates, strong demand, and improved liquidity, says CBRE Q1 report.
 nishathapa
Asia Pacific, April 2026: Vietnam and India have emerged as leading destinations for hotel investment in the Asia Pacific region, supported by rising room rates, improving performance metrics, and stronger liquidity conditions, according to the Q1 2026 Asia Pacific Hotel Trends report released by CBRE.
Vietnam and India Drive Regional Investment Momentum
The report identifies Vietnam and India as the most active markets for hotel investment activity in the region, as investors respond to improving operational performance and increasing returns. According to CBRE, both markets are witnessing heightened investor interest as fundamentals strengthen, particularly in terms of revenue growth and asset performance.
In Vietnam, the hotel sector continues to perform strongly despite rising operating costs. The country has recorded sustained growth in tourist arrivals, while new hotel supply remains relatively limited. This combination has supported a steady rise in key performance indicators, making the market attractive for both domestic and international investors.
India’s hospitality sector is similarly gaining momentum, driven by robust domestic travel demand and a growing Meetings, Incentives, Conferences and Exhibitions (MICE) segment. The report highlights increasing transaction activity in the Indian market, reflecting rising investor confidence and competition for quality hotel assets.
RevPAR Growth and Demand Strengthen Investment Case
Vietnam’s major urban and resort destinations, including Ho Chi Minh City and Hanoi, have recorded notable growth in Revenue Per Available Room (RevPAR). This increase is attributed to strong occupancy levels and improving average daily rates, supported by consistent inbound tourism demand.
The report notes that this performance has led investors to target a mix of city-center hotels and leisure-oriented assets, as both segments benefit from the country’s tourism recovery and limited new supply pipeline.
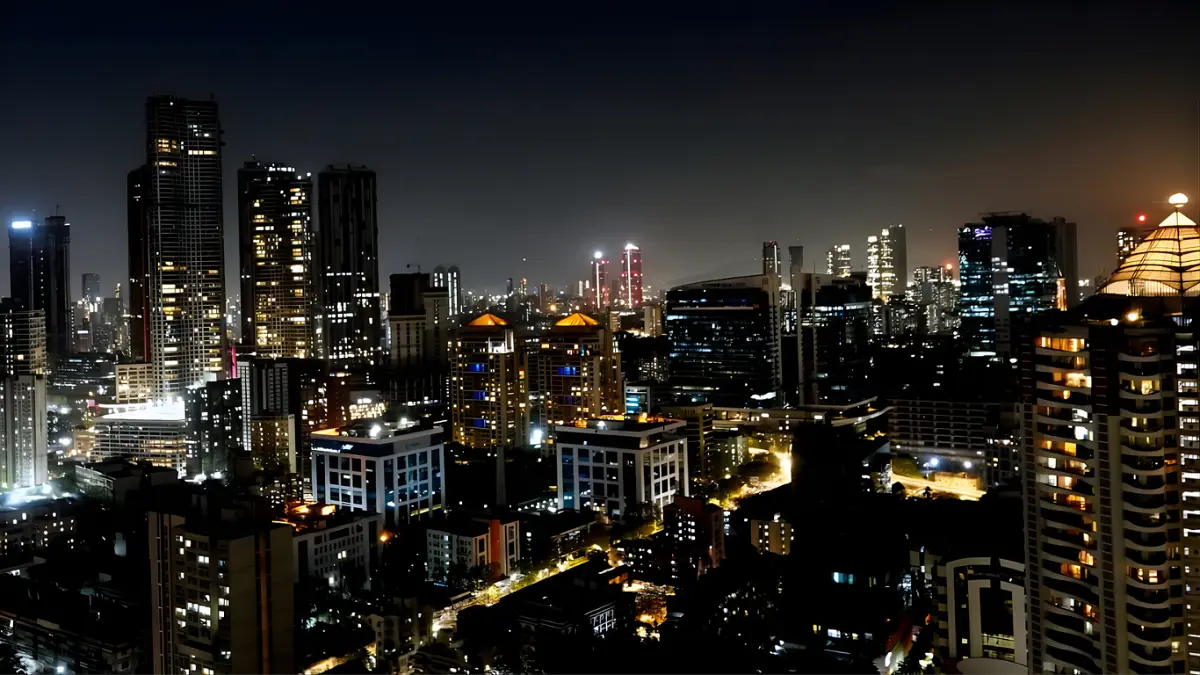
India’s market dynamics are also contributing to rising hotel performance metrics. Mumbai is highlighted as a key market, having recorded the highest hotel occupancy levels among Indian cities in the previous year. Strong pricing power, coupled with steady demand, has reinforced the city’s position as a focal point for investment activity.
Infrastructure and Domestic Travel Fuel India Growth
The report links India’s strong performance to a combination of domestic travel demand and infrastructure development. Growth in the MICE segment has played a significant role in sustaining occupancy and rate growth across major cities.
Additionally, upcoming infrastructure projects, including the Navi Mumbai airport, are expected to further enhance connectivity and support long-term demand for hotel accommodation in key markets. These developments are contributing to increased investor interest in both existing assets and new developments.
The expansion of domestic travel continues to act as a stabilising factor for the Indian hospitality sector, reducing reliance on international demand and supporting consistent performance across different market cycles.
Rising Room Rates and Liquidity Attract Investors
CBRE attributes the growing investor appetite in both Vietnam and India to sustained growth in room rates and improving liquidity options. These factors are enabling hotel owners and operators to achieve stronger returns, while also creating more exit opportunities for investors.
“Investor activity continues to build in Vietnam and India on the back of significant growth in room rates and enhanced liquidity options,” said Steve Carroll, Head of Hotels & Hospitality Asia Pacific at CBRE.
The report suggests that the combination of operational performance and market liquidity is creating favourable conditions for both acquisitions and new investments, particularly in markets where supply remains constrained.
APAC Outlook Supported by Travel Recovery and Events
Looking ahead, CBRE expects hotel performance across Asia Pacific to remain strong through 2026, supported by domestic travel and improving inter-regional tourism flows. The recovery in travel demand is expected to continue driving occupancy and rate growth across key markets.
In the near term, the report highlights opportunities for hotel owners to capitalise on soft-brand conversions and event-driven demand. Large-scale events such as concerts, exhibitions, and conventions are expected to play a role in boosting occupancy and revenue in major cities.
Markets that can effectively leverage these demand drivers are likely to capture additional growth, particularly in segments where experiential travel and flexible brand positioning are gaining traction.
The findings reflect a broader shift in Asia Pacific’s hospitality landscape, where performance-driven markets like Vietnam and India are attracting increased capital flows. As room rates continue to rise and demand remains resilient, both countries are positioned as key growth engines within the region’s hotel investment cycle.