AirAsia Seeks $1B Funding After $19B Aircraft Order
AirAsia is seeking up to $1 billion in funding after an RM830.5 million loss, while cutting capacity by up to 25% and returning 25 older aircraft to lessors.
 Jishan Khan
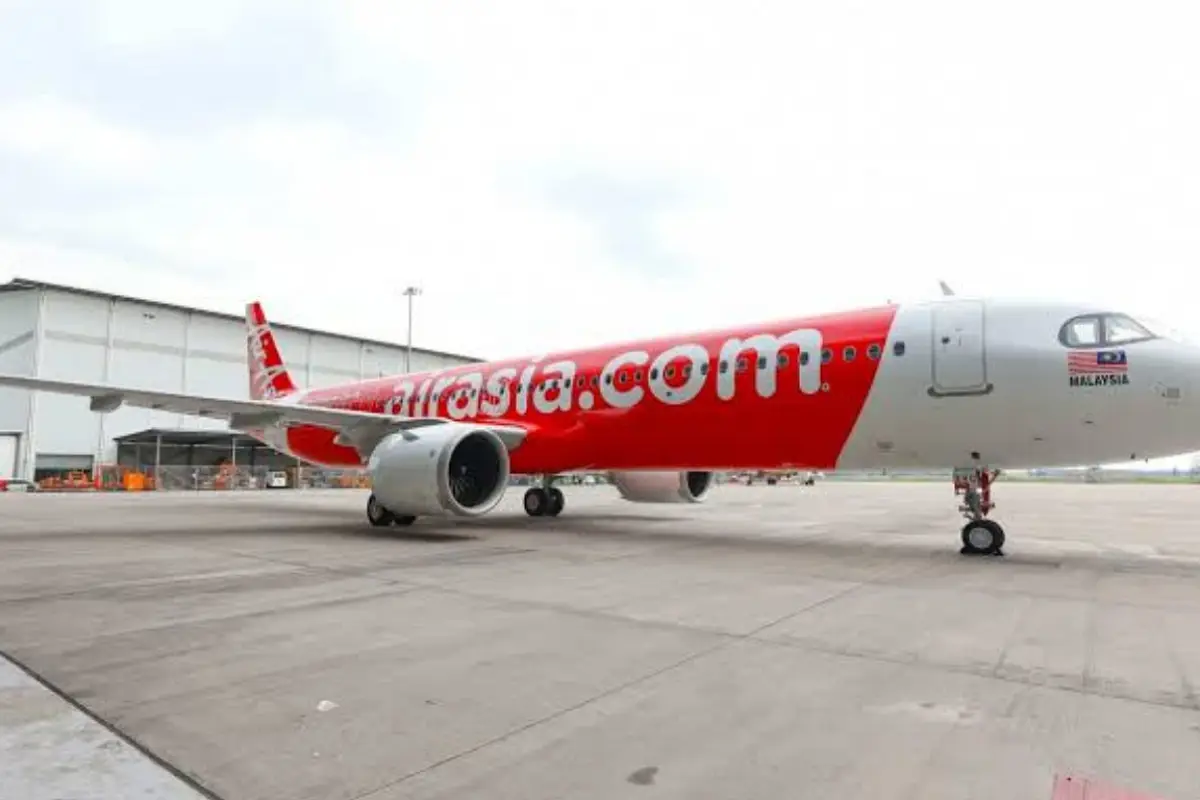
AirAsia Placed a $19 Billion Aircraft Order in May, Three Months Later It's Cutting Capacity 25% and Seeking $1 Billion Just to Stay Liquid
AirAsia Group is in advanced talks with local and international financial institutions for up to USD 1 billion in funding, alongside MYR 700 million in local facilities and a targeted bond issuance, after posting a RM830.5 million net loss for the quarter ended June 30, 2026, its widest quarterly loss in years. The group is cutting third-quarter capacity by 20-25% year-on-year, returning 25 older aircraft to lessors, and describing Q2 as its financial "floor." Three months before this liquidity crunch became public, AirAsia signed the largest single order in Airbus A220 programme history, 150 aircraft worth roughly USD 19 billion at list price.
That timing is not a contradiction. It is exactly how founder Tony Fernandes says AirAsia has always operated.
The Fuel Shock That Hit Every Route Simultaneously
Average jet fuel prices hit USD 183 per barrel in Q2 2026, a 58% year-on-year surge driven by the Iran conflict, the same crisis that has forced capacity cuts, fleet groundings and profit warnings across nearly every airline covered in this feed over the past six months. AirAsia's fuel bill jumped in lockstep with every other carrier's, but the group's response reveals something about its underlying financial structure that distinguishes it from carriers like Cathay Pacific or Lufthansa, which are managing the same shock from a position of much greater balance sheet strength.
AirAsia still generated positive EBITDA of RM442.6 million in the quarter, even after fuel costs and an 11% capacity cut, evidence that the underlying network remains commercially viable. But RM331 million in foreign exchange losses from the ringgit, Thai baht, Indonesian rupiah and Philippine peso all depreciating against the dollar simultaneously turned an operationally survivable quarter into a headline net loss that alarmed the market. CEO Bo Lingam's own framing, describing 2Q26 as the "floor quarter" and expecting fuel prices to ease from their extreme peak, is a bet that the worst has already passed, not a warning that worse is coming.
Why 25 Aircraft Are Going Back to Lessors While 150 New Ones Are on Order
The apparent contradiction resolves once you separate AirAsia's near-term cost structure from its long-term fleet architecture. The 25 aircraft being returned in FY2026 are older A320-200s, concentrated in Indonesia AirAsia and Philippines AirAsia operations, markets where capacity has been reduced specifically because they were underperforming financially in Q2. Returning them eliminates fixed lease costs the group is paying regardless of how many passengers those aircraft actually carry. That is straightforward cost discipline, not retreat.
The A220 order and the 50-plus-20 A321XLR agreement worth USD 12.25 billion are an entirely different decision, made on an entirely different timeline. Airbus deliveries begin in 2028, meaning today's liquidity crunch and the new aircraft arriving in two years are not competing for the same capital in the same quarter. AirAsia locked in A220 pricing and delivery slots in May 2026, at exactly the moment fuel costs were spiking and the broader market was nervous, precisely the environment in which aircraft manufacturers are most willing to negotiate favourable terms with a committed buyer. Fernandes said it directly, "We've taken a clear-eyed view of the risks, and what we see is an opportunity to lock in strategic capacity on terms that will be very hard to replicate later."
The Pass-Through Strategy That Is Actually Working
The detail that should give investors more confidence than the headline loss number suggests is AirAsia's demonstrated ability to push fuel costs onto fares without collapsing demand. April fares grew just 4% year-on-year because a large share of seat inventory had already been sold before the fuel spike hit. By May and June, with dynamic pricing fully repriced, fares grew over 20% year-on-year while non-fuel unit costs dropped 7%. Revenue per available seat kilometre rose 11% for the quarter even as capacity fell 11%, the group prioritised yield over volume and largely succeeded, achieving what management describes as a 70% pass-through rate on the fuel cost increase.
That pricing power matters enormously for how the current liquidity raise should be read. A USD 1 billion financing round for an airline that cannot pass costs through to customers is a distress signal. The same raise for an airline that has just proven it can reprice 70% of a historic fuel spike within eight weeks is closer to a working capital bridge, insurance against a worst-case scenario the group's own commercial performance suggests it is unlikely to need in full.
What Q4 Is Supposed to Prove
AirAsia plans to restore capacity toward pre-crisis levels in Q4 as year-end travel demand strengthens, with Thailand specifically expected to narrow losses in Q3 and return to profit in Q4. Forward bookings across the group's core ASEAN network are tracking in line with the previous year, evidence that underlying passenger demand has not eroded, only the cost of serving it has spiked temporarily.
The USD 1 billion liquidity search, the 25 returned aircraft and the 20-25% capacity cut are all measures designed to get AirAsia through the worst quarter of the fuel shock intact. The 150-aircraft A220 order and the A321XLR fleet plan are the bet on what the airline looks like once it gets there. Whether both strategies can be executed simultaneously without one undermining the other is the real test, and it is a test Fernandes has explicitly framed as the kind AirAsia has built its entire twenty-year history on passing.