Hotel Demand and Room Rates Diverge from Office Occupancy
Hotel demand and room rates continue climbing even as office occupancy lags, with inflation tying the two sectors together in unexpected ways.
 RUKAIYA KADIWAL
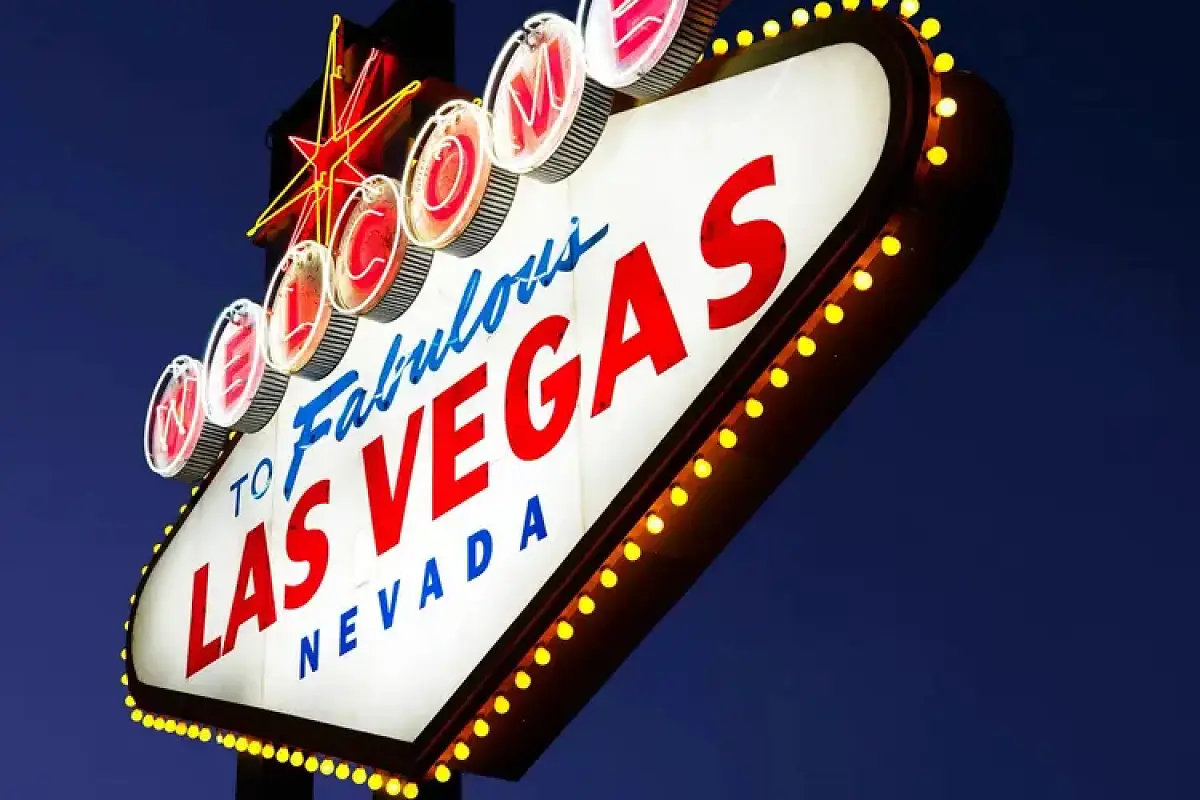
Beneath the neon glow of the Welcome to Fabulous Las Vegas sign, the story two industries are telling about the same city no longer quite matches. Office towers downtown sit with emptier floors than they did before remote work reshaped the American workweek, yet a few miles away, hotel front desks keep quoting higher prices for the same room, night after night. That contradiction sits at the center of new Hotel Demand and Room Rates analysis from CoStar, which finds that even as office use and hotel demand pull apart, their pricing has kept moving in a strikingly similar direction.
A Connection That Should Have Broken
For years, weekday hotel demand and office occupancy moved together almost by default, business travelers filling both. Remote work changed that relationship, thinning out office floors without necessarily thinning out hotel corridors, since business trips, conferences and client visits continued even as daily commuting habits shifted. Logic would suggest hotel pricing should have softened alongside emptier offices. Instead, weekday transient average daily rates have continued climbing across the top 25 U.S. regions, moving in tandem with office rents rather than office occupancy.
Where Inflation Does the Connecting
What ties the two sectors together now is not shared demand but shared cost pressure. Rising construction, labor and operating expenses have pushed both office rents and hotel room rates upward regardless of how full either space actually is. It is a subtler kind of correlation than the old commuter driven link, one built on inflation rather than occupancy, and it explains why room rates keep rising in markets where office towers have not filled back up.
Las Vegas as the Clearest Example
Few markets illustrate that divergence as sharply as Las Vegas. Since 2019, the city has recorded some of the steepest increases in both weekday transient average daily rates and office rent, two figures moving upward together despite representing very different kinds of demand. For a city built almost entirely around hospitality, that pairing suggests something specific, room rates climbing on their own economic logic, tourism, convention business, entertainment draw, largely independent of whatever is happening inside the city's office towers.
What This Means for Hotel Operators
For hotel owners and operators watching these trends, the takeaway is not straightforward comfort. Rising room rates driven by cost inflation rather than genuine demand growth can mask underlying softness, a hotel filling rooms at higher prices is not necessarily proof that more travellers are arriving, only that the cost of serving them has gone up. Distinguishing between price growth backed by real demand and price growth driven purely by rising expenses has become a more urgent analytical task across the industry.
A Market Worth Watching Closely
As markets continue adjusting to permanently altered office use patterns, tracking how hospitality developments across the country respond to these pricing pressures will matter as much as the headline rate figures themselves, since new supply entering a market can either absorb rising costs or amplify the pricing gap further.
What emerges from this data is less a single trend than a reminder that hotel pricing and office pricing can rise together for entirely different reasons. The neon sign in Las Vegas has welcomed visitors for decades regardless of what the office market was doing. Increasingly, that independence extends to the numbers as well.
More information is available on the official website at costar.com.