IndiGo Wins Relief in $48M Tax Dispute Case in Delhi
IndiGo secures relief in INR4.8 billion tax dispute as Delhi High Court blocks coercive action while case continues.
 Jishan Khan
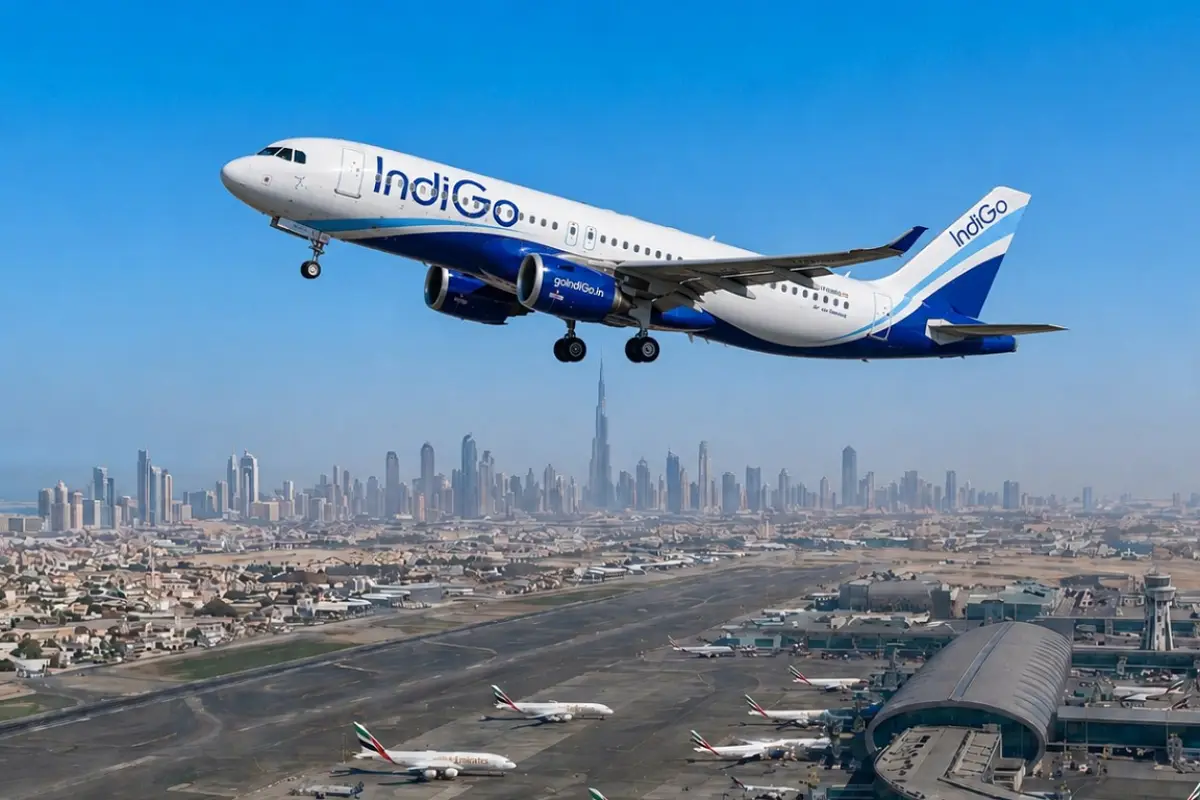
Delhi High Court Gives IndiGo a $48 Million Tax Dispute Win, And the Timing Could Not Be Better for India's Largest Airline
A court order blocking coercive tax action. A disputed liability of INR 4.8 billion. And a ruling that gives IndiGo the legal breathing room it needs while one of Indian aviation's biggest tax battles plays out in the background.
IndiGo has secured a significant legal win at the Delhi High Court in a sales tax dispute that has been running long enough and grown large enough, INR 4.8 billion, approximately $48 million, that its resolution matters well beyond the immediate financial relief it provides.
The court has directed tax officials not to take coercive action against the airline while the matter continues through the legal process. That direction is the critical detail. It means IndiGo does not have to worry about forced recovery of disputed tax demands while it builds its legal challenge, no asset seizures, no forced payments, no operational disruption triggered by tax enforcement actions that the airline is contesting as unjustified in the first place.
It is not a final verdict. The dispute itself continues. But in the practical world of airline treasury management and operational planning, the difference between a disputed tax demand that regulators can enforce aggressively and one where a High Court has explicitly told officials to stand down pending further proceedings is enormous.
What a Sales Tax Dispute on Aircraft Transactions Actually Involves
The specific nature of this dispute, sales tax demands linked to aircraft-related transactions and financial claims, sits in a part of Indian aviation taxation that has historically been one of the most contested and complex areas of the sector's regulatory environment.
Aircraft transactions in India involve multiple layers of financial and legal complexity. Sale and leaseback arrangements, operating lease structures, maintenance reserves, aircraft redelivery payments, and the financing instruments that airlines use to manage their fleet costs all create taxable events whose classification has been genuinely disputed between carriers and tax authorities for years.
The core disagreement in cases like this typically involves whether specific transactions constitute taxable sales, whether the applicable tax rates have been correctly assessed, and whether the jurisdiction claiming the tax liability has the legal authority to do so under the applicable statutory framework. None of these questions have simple answers when the transactions involve international lessors, cross-border financing structures, and aircraft that may have been registered, operated, and maintained across multiple jurisdictions.
IndiGo's position, that the INR 4.8 billion demand is unjustified and worth fighting through the courts, reflects a judgment that the tax authorities have either misclassified the transactions, misapplied the applicable rates, or exceeded their jurisdictional authority in raising the demands. The Delhi High Court's willingness to issue a direction against coercive action suggests the airline's legal arguments were strong enough to warrant that interim protection, a threshold that Indian courts do not apply automatically.
Why This Matters for IndiGo's Financial Position Specifically
IndiGo's financial trajectory in 2026 makes this ruling particularly well-timed. The airline has been working to consolidate its position as India's dominant carrier, a position built on aggressive domestic expansion, international route development, and the operational scale that comes with operating the largest fleet of any Indian carrier.
Maintaining that trajectory requires capital. Fleet expansion, route development, new aircraft deposits, maintenance infrastructure, and the working capital requirements of an airline growing as fast as IndiGo's operational ambitions demand all compete for the same financial resources.
A coercive tax demand of $48 million landing on IndiGo's treasury at the wrong moment in its cash flow cycle would not threaten the airline's existence, it is too large and too well-capitalised for a single dispute of this size to be existential. But it would create exactly the kind of unnecessary financial friction that disrupts capital allocation planning and diverts management attention from the operational and strategic priorities that IndiGo's competitive position depends on.
The Delhi High Court's ruling removes that friction for now. It lets IndiGo continue expanding, investing, and operating without the distraction of defending against enforcement actions on a liability it believes it does not owe.
The Broader Pattern of Aviation Tax Disputes in India
IndiGo's case is not an isolated dispute in an otherwise settled tax environment. Indian aviation has a well-documented history of complex, long-running tax controversies between carriers and authorities, at the central, state, and municipal level, that reflect the genuine complexity of taxing an industry whose transactions regularly cross jurisdictional boundaries in ways that the original drafting of applicable tax legislation did not fully anticipate.
SpiceJet, Air India, and IndiGo itself have all navigated significant tax disputes over the years. The disputes tend to cluster around specific transaction types, particularly the aircraft financing and leasing structures that Indian carriers use to manage their fleet costs, where the gap between commercial practice and the literal application of tax legislation creates genuine ambiguity that both carriers and authorities argue in their own favour.
The resolution of those disputes through the court system is slow, expensive, and uncertain in ways that create ongoing operational risk for carriers managing large tax contingency positions. A ruling like the Delhi High Court's direction in the IndiGo case does not resolve the underlying ambiguity. But it does establish that courts are willing to provide interim protection to airlines challenging demands that they can demonstrate are genuinely contested rather than simply deferred.
That precedent has value beyond IndiGo's specific dispute. It signals to Indian carriers broadly that the legal system offers a viable mechanism for contesting aggressive tax enforcement actions while substantive arguments are heard, a signal that matters when the alternative is paying disputed demands under protest to avoid coercive enforcement and then fighting for refunds through a process that can take longer than the original dispute.
What Comes Next
The Delhi High Court's direction is interim protection, not final resolution. The INR 4.8 billion dispute will continue through the legal process, with tax authorities presumably maintaining their position that the demands are valid and IndiGo continuing to challenge them on whatever grounds its legal team has identified as strongest.
The timeline for final resolution in Indian tax litigation at this scale is measured in years rather than months. That is not unusual and not itself a concern for IndiGo, the airline has the legal resources and the financial position to sustain a prolonged dispute without operational consequence.
What matters in the near term is that the protection the court has provided holds, that tax officials respect the direction not to take coercive action, and that the substantive legal arguments IndiGo is advancing get a proper hearing on their merits rather than being rendered moot by enforcement actions that the court has now explicitly put on hold.
For India's largest airline, continuing to fly, continuing to grow, and continuing to expand its network without a $48 million tax enforcement action creating unnecessary turbulence in the background is exactly the outcome this ruling delivers.
The legal battle continues. For now IndiGo is flying through it with the court's protection in place, and in the high-stakes world of airline treasury management, that is exactly the kind of win that matters most when it arrives.