Korean Air Secures $300M With Dollar Bond
Korean Air raises $300 million through its first commercial bank-backed dollar bond as strong investor demand signals confidence ahead of its Asiana merger.
 Jishan Khan
Korean Air Just Borrowed From a Commercial Bank for the First Time, and the Spread Says Everything About Its Post-Merger Standing
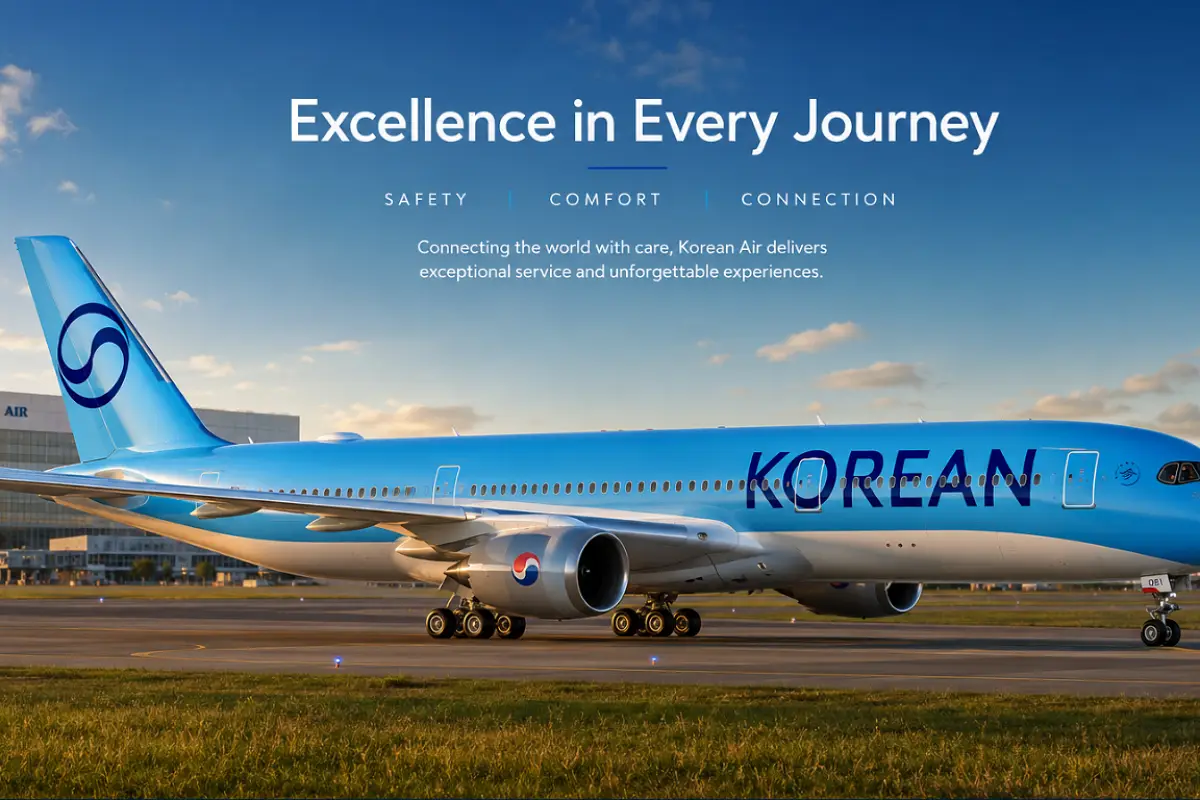
Korean Air priced a USD 300 million three-year Eurobond on August 5, 2026, guaranteed by KB Kookmin Bank at 57 basis points over US Treasury yields, 33 basis points tighter than initial guidance after strong demand across Asian and European markets. The new issue premium landed at approximately zero, versus the 5 to 10 basis points typical for recent Korean issuers. The bond follows a JPY 20 billion Samurai bond in July guaranteed by the Export-Import Bank of Korea.
Two international bond deals in three weeks. Different currencies, different guarantors, zero new issue premium. The capital markets are telling Korean Air it has arrived at a new tier.
The Guarantor Switch That Markets Noticed
Korean Air's previous dollar bonds have carried guarantees from state-run banks, the Korea Development Bank and the Export-Import Bank of Korea. The KB Kookmin Bank guarantee on this Eurobond is the first time a commercial bank has backed a Korean Air dollar issuance. That distinction is more significant than it appears. State bank guarantees reflect government support for a national carrier, useful, but expected. A commercial bank guarantee signals that Korea's largest private lender has independently assessed Korean Air's credit risk and decided the merged entity is worth backing on commercial terms.
KB Kookmin reportedly offered more aggressive guarantee terms than the state banks, factoring in the global stature of the merged Korean Air. The bank is making a bet on what Korean Air looks like post-integration, not what it was before the Asiana acquisition. And the Aa3 rating the KB guarantee secured from Moody's, matching the bank's own rating, gave international investors a credit anchor that drove the book well beyond the minimum needed to tighten pricing 33 basis points from guidance.
The USD 36.2 Billion Bill Behind the Bond
The financing activity is not happening in a vacuum. Korean Air last year announced plans to invest USD 36.2 billion to add 103 Boeing aircraft to its fleet by 2030, comprising 20 Boeing 777-9s, 25 787-10s, 50 737-10s and eight 777-8F freighters, with deliveries scheduled through the late 2030s. That USD 36.2 billion does not sit in a Korean Air bank account waiting to be deployed. It gets funded in tranches, through a combination of cash flow from operations, asset-backed financing on individual aircraft, and unsecured market debt like the bonds being raised now.
The Samurai bond and the Eurobond together raised approximately USD 426 million in six weeks. Against a USD 36.2 billion capex programme that is a modest opening instalment, but it establishes pricing benchmarks, demonstrates market access across multiple currencies simultaneously, and builds the investor relationships that will be needed when the larger financing tranches arrive with 777-9 and 787-10 deliveries from 2027 onward.
The Unified Korean Air That Changes the Calculation
The unified Korean Air, incorporating Asiana Airlines, officially begins operations in December 2026. The merged entity will be significantly larger than either carrier was independently, a combined fleet, combined route network, combined loyalty programme and combined revenue base that gives bond investors a fundamentally different credit story than Korean Air presented before the acquisition closed.
The zero new issue premium on the August Eurobond is the market's real-time verdict on that story. Airlines typically pay a premium above the theoretical fair value of their debt to compensate investors for taking the risk of a new issuance. Korean Air paid nothing extra. Investors bought at fair value, a signal that demand was sufficient to absorb the full USD 300 million without any incentive beyond the rate itself.
For an airline that has spent three years managing the complexity of absorbing a rival carrier while navigating the Iran conflict's fuel shock, a commercial bank guarantee, zero new issue premium and 33 basis points of tightening in a single bookbuild is as clean a capital markets outcome as Korean aviation has produced in years.