Malaysia Prepares Contingency Plans for AirAsia Routes
Malaysia is discussing contingency plans for AirAsia's routes with Malaysia Airlines and Batik Air as the airline works to secure refinancing.
 Jishan Khan
"No Takeover Has Been Decided" Is Doing a Lot of Work in This Story, Six Different Outlets Used Almost the Same Sentence
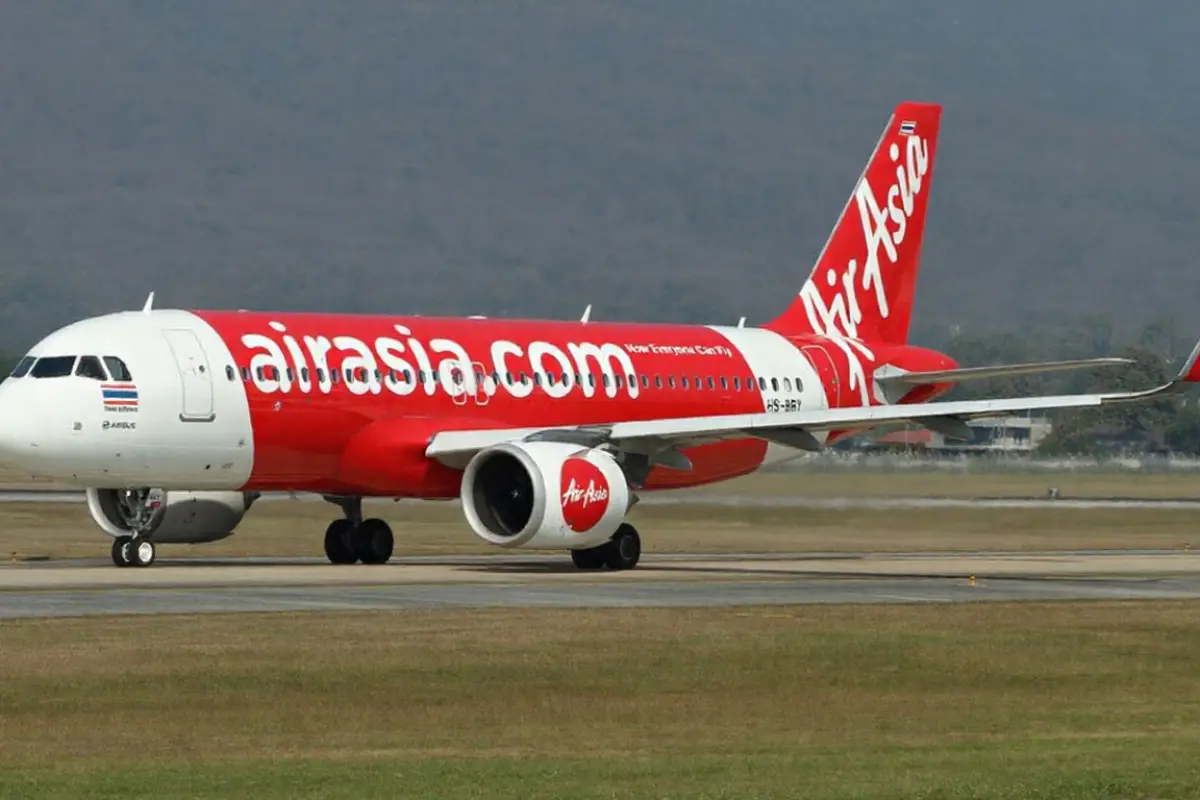
Malaysia's Ministry of Finance and state airport operator Malaysia Airports Holdings Berhad have intensified contingency discussions with Malaysia Airlines and Batik Air over how the domestic market would absorb AirAsia's routes and passengers if the low-cost carrier's finances deteriorate further, according to Reuters sources cited across multiple outlets this week. AirAsia Malaysia takeover is therefore being discussed as a contingency scenario, not a confirmed transaction. AirAsia controls close to 60% of Malaysia's domestic flights and roughly 40% of the country's total air travel market, a concentration level that makes even the possibility of disruption a matter of genuine national infrastructure planning, not merely one airline's balance sheet problem. Every source is careful to repeat the same caveat almost verbatim: this is scenario planning, not a decision to transfer operations or execute a takeover.
That repeated caveat is worth taking at face value rather than reading as spin. It reflects something specific about how Malaysia's government appears to be approaching this crisis, quietly stress-testing what a worst-case outcome would require, while AirAsia's own restructuring and AirAsia refinancing effort is still actively underway and has not yet failed.
Why the Government's Own Data Doesn't Quite Match AirAsia's 60% Claim
One detail worth flagging precisely because it complicates the headline figure everyone is repeating: AirAsia itself states it controls approximately 60% of domestic flights and 40% of the total market. But data from Malaysia's own Civil Aviation Authority, covering the first quarter of 2026, puts AirAsia specifically at 33.7% of passenger traffic, with AirAsia X, the group's separate long-haul low-cost arm, contributing a further 4%, for a combined figure closer to 38% rather than AirAsia's self-reported 40%. That gap is modest and may simply reflect AirAsia measuring domestic flight share differently than CAAM measures overall passenger traffic share, but it is a reminder that even the core statistic anchoring this entire crisis, exactly how dominant AirAsia actually is, carries some genuine measurement ambiguity depending on whose data is being cited, a detail that matters when policymakers are trying to size a contingency plan against a specific market-share number.
The Specific Condition That Reveals This Is Genuinely Difficult to Execute, Not Just Politically Sensitive
The single most operationally important detail in this entire story is the condition Malaysia Airlines and Batik Air have reportedly attached to any involvement: they would only take on AirAsia's operations if they could also assume its aircraft leases. That is not a minor negotiating point, it is the structural bottleneck that determines whether an AirAsia Malaysia takeover scenario is even mechanically possible in the way headlines imply.
An airline's ability to absorb a competitor's routes and passengers depends almost entirely on having the aircraft to actually fly those routes. Malaysia Airlines and Batik Air cannot simply announce they are absorbing AirAsia's Kota Kinabalu-Kuching route or its Kuala Lumpur-Langkawi frequency without physically having additional aircraft available to operate it, and building that capacity organically, through their own new orders or lease agreements, takes years, not months. The only way either carrier could meaningfully absorb AirAsia's actual flying at anything resembling the current scale, on anything resembling a workable timeline, is by inheriting the physical aircraft AirAsia already operates under lease, meaning any real transfer scenario would functionally require AirAsia's existing lessors to agree to reassign those lease contracts to a different Malaysian carrier entirely. That is a complex, multi-party negotiation involving international leasing companies with their own credit assessments and contractual terms, not something Malaysia's government or either airline could simply decide unilaterally.
Why AirAsia Owing Its Own Landlord Money Is the Detail That Grounds This in Reality
AirAsia owes Malaysia Airports Holdings Berhad, the very state entity now helping coordinate contingency planning with AirAsia's competitors, at least RM500 million in unpaid landing and parking fees, with repayment extensions already arranged. That detail places MAHB in a genuinely unusual dual position: it is simultaneously AirAsia's creditor, owed real money the airline has not yet paid, and one of the two government bodies now quietly organising what happens to Malaysian domestic aviation if AirAsia cannot pay its debts at all. MAHB's incentive structure here is not neutral, an airport operator has every reason to want its largest domestic tenant to remain solvent and flying, since AirAsia's roughly 60% domestic share generates a correspondingly enormous share of MAHB's own landing fee and terminal revenue, even while that same tenant currently owes MAHB half a billion ringgit it has not paid.
Why This Is Fundamentally Different From Malaysia's Earlier AirAsia Reviews
This feed has already tracked the earlier stage of this exact crisis, the Ministry of Finance's engagement of Alton Aviation Consultancy specifically to assess AirAsia's funding needs, alongside the airline's own pursuit of up to $1 billion in international debt financing plus RM700 million in local credit facilities to refinance and consolidate existing liabilities. That earlier engagement was explicitly framed around whether AirAsia needed government financial support to survive its immediate liquidity crunch. This week's development is a materially different and more consequential planning exercise, it assumes AirAsia's own AirAsia refinancing effort might not fully succeed, and asks what happens operationally to Malaysian domestic connectivity in that specific scenario, independent of whatever financial support Alton's review ultimately recommends.
Running both processes in parallel, one assessing whether AirAsia can be financially stabilised, the other quietly mapping what happens if it cannot be, is precisely how a government treats a systemically important company: hoping for the first outcome while genuinely preparing for the second, rather than assuming the financial rescue will simply work.
Why AirAsia's Own PN17 History Makes This Especially Sensitive
The broader context this feed's earlier coverage established matters directly here: AirAsia's parent group Capital A has been working through Malaysia's PN17 financially distressed company classification, following a complex restructuring in which AirAsia X Berhad completed its acquisition of AirAsia Berhad and the wider AirAsia Aviation Group in January 2026 specifically to exit that distressed status. A government now quietly discussing contingency route-transfer scenarios with AirAsia's direct competitors, less than a year after the airline group completed a restructuring explicitly designed to demonstrate renewed financial stability, is a genuinely uncomfortable signal about how much confidence that restructuring has actually restored, regardless of how carefully every party involved insists no takeover decision has been made.
What Happens to Ordinary Travellers If Any of This Actually Materialises
The practical stakes extend well beyond corporate balance sheets. AirAsia functions as what multiple outlets accurately describe as the indispensable aerial bridge connecting Peninsular Malaysia with Sabah and Sarawak across more than 600 kilometres of open ocean, a physical connectivity role no alternative transport mode can substitute for at comparable cost or speed. Tourism Malaysia has separately confirmed that international connectivity from markets like India, which sent more than 1.5 million visitors in 2025, depends partly on onward domestic connections that AirAsia, alongside Malaysia Airlines, Batik Air and IndiGo, currently provides collectively. Any reduction in AirAsia's domestic capacity, even well short of a full operational collapse, would almost certainly translate into higher average domestic fares simply through reduced seat supply, disproportionately affecting exactly the price-sensitive leisure and VFR travellers who have relied on AirAsia's low-cost model to make Peninsular-Borneo travel affordable in the first place.
Why Nobody Involved Wants to Say the Word "Bailout"
AirAsia's own public position remains that it is focused on maintaining stable operations and that underlying travel demand remains strong, language nearly identical to the reassurances this feed has tracked from other financially pressured carriers throughout 2026, including AirAsia's own earlier statements when the Alton Aviation review first became public. The Ministry of Finance, Malaysia Airlines and Batik Air have all declined to comment publicly on the specifics of these contingency discussions, a silence that is itself informative: none of the parties directly involved wants to be quoted confirming details of a plan explicitly premised on one of Malaysia's most significant private employers and its dominant domestic aviation provider potentially failing to stabilise its own finances.
That silence will likely hold until one of two things happens, either AirAsia's roughly $1.15 billion refinancing effort succeeds, rendering this entire contingency exercise a hypothetical that never needed to be executed, or the refinancing falls short, forcing Malaysia's government to move from quietly asking Malaysia Airlines and Batik Air what they could absorb, to actually deciding whether, and how, to make that absorption happen. That is the point where the AirAsia contingency plan would move from scenario planning into an actual operational response.