Singapore Airlines Eyes More Investment in Air India
Singapore Airlines reported SGD 945.2 million in losses from its Air India investment but remains committed to the airline's long-term turnaround.
 Jishan Khan
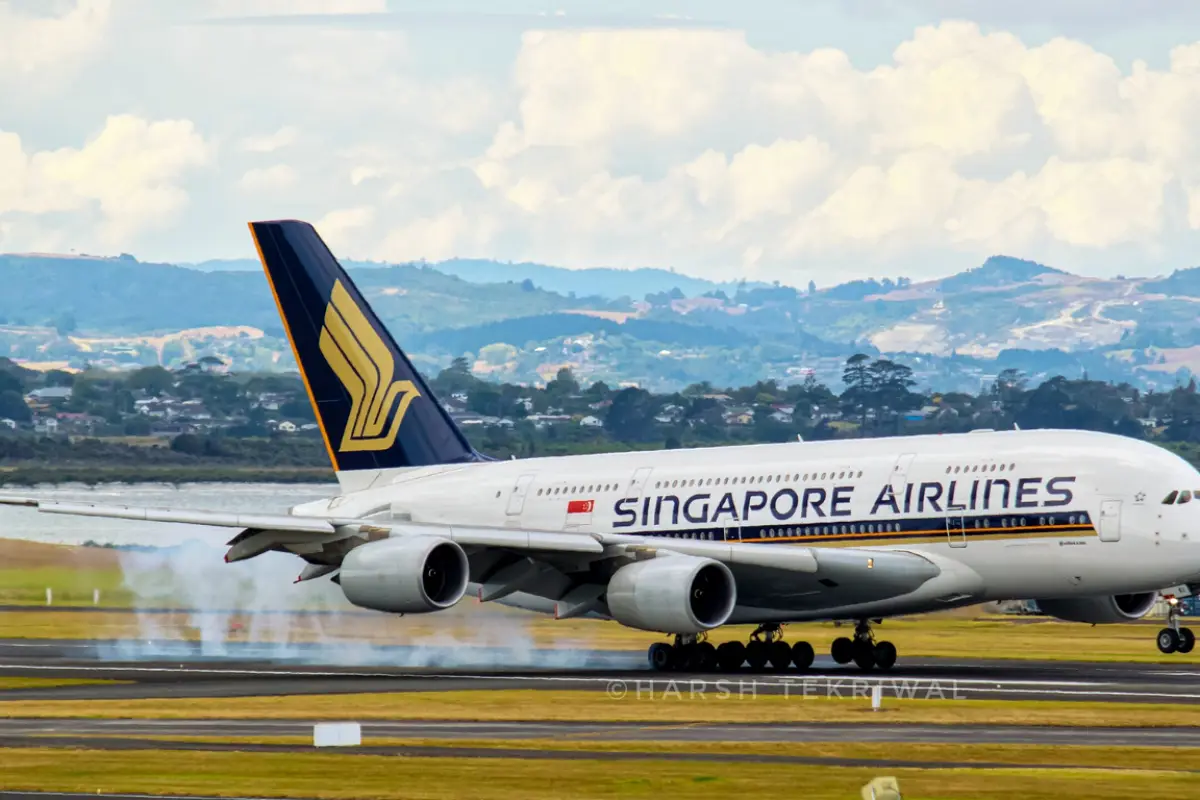
Singapore Airlines Lost $731 Million on Air India Last Year, and Just Said It Will Put In More
Singapore Airlines recognised SGD 945.2 million in losses from its Air India stake for the year ended March 31, 2026, while the carrying value of that stake fell from SGD 2 billion to SGD 1.1 billion in a single year. Despite that, the airline told shareholders on July 17 that it remains open to additional capital injections and described Air India as a pillar of its multi-hub strategy. Air India's full-year loss after tax came in above INR 220 billion, roughly SGD 3 billion, materially wider than earlier expectations.
Singapore Airlines absorbed a $731 million loss on a single investment and its public response was to say it might put in more. That is either remarkable conviction or a trap it cannot escape. The answer is probably both.
The Year That Made Everything Worse
Air India was battered in FY2026 by a fatal Boeing 787-8 crash that killed more than 240 people, Pakistan's closure of its airspace to Indian carriers following the India-Pakistan military confrontation in May 2026, and the Iran conflict driving fuel costs up sharply. Any one of those events would have damaged a recovering airline's financials significantly. All three arriving in the same fiscal year on top of an already loss-making carrier undergoing the most complex airline integration in Indian aviation history produced a loss number that shocked even analysts who had been pessimistic.
Air India's losses reflect multiple overlapping pressures, higher operating costs from airspace disruptions, reduced international capacity following the Boeing 787 incident, and continued near-term funding requirements that are now materially higher than initially expected. The SGD 880 million in additional capital SIA committed at the time of the Vistara merger in November 2024 now looks insufficient. Air India is seeking at least 100 billion rupees, approximately SGD 1.47 billion, in financial support from Singapore Airlines and Tata Sons combined, a figure well above the original commitment.
Why Singapore Airlines Is Still In
SIA CEO Goh Choon Phong called the turnaround a "long game" with "no shortcut," reaffirming support even as the carrying value of the stake has fallen to SGD 1.1 billion against a cost of SGD 2.1 billion. The language is deliberate. Singapore Airlines does not have a domestic aviation market. Its home country of 5.9 million people cannot generate the passenger volumes that sustain a major international carrier on their own, SIA's entire business model depends on connecting international traffic flows through Changi. India, with 1.4 billion people and one of the world's fastest-growing aviation markets, is exactly the kind of domestic traffic engine SIA cannot build at home.
SIA describes the Air India investment as providing access to India's domestic market and international traffic flows through Indian hubs, with its CEO serving on Air India's board and executives embedded in operational, engineering and commercial roles. The investment is not a financial instrument, it is market access structured as equity, and the strategic value of that access does not disappear because Air India had a catastrophic year.
Ironically, SIA's core business posted record revenue of SGD 20.5 billion and a 39% jump in operating profit in the same year, as it captured spillover traffic from Middle Eastern carriers disrupted by the Iran conflict by expanding capacity to Europe. The parent is strong enough to absorb the subsidiary's losses, for now.
The Point Where Conviction Becomes a Problem
The financial mathematics are becoming harder to ignore. A larger-than-expected capital injection in this round could start to constrain SIA's dividend capacity, according to DBS Group Research, and SIA shareholders who have watched the Air India stake's carrying value halve in twelve months are not a passive audience. The airline's AGM on July 24 will be the first opportunity for retail investors to press management directly on how much more they are prepared to commit and under what conditions they would reconsider.
Analysts say there is a chance SIA could eventually sell its stake to Tata or another buyer if losses continue widening, though that outcome would require Tata's agreement and a market willing to absorb the position. The more likely scenario, at least for now, is more capital, more patience, and more of what Goh called the long game.
India is building airports at a pace unseen in its history. Air India is buying 470 aircraft. The country is targeting 300 million annual passengers by 2030. Singapore Airlines got into this investment because it saw that future clearly, and a year of catastrophic events has not changed what the future looks like, only what the path to it costs.