Europe Short Term Rental Market Reveals August Shift
Europe Short Term Rental Market posted 4.3% RevPAR growth in August as rates climbed 7.5%, even as occupancy and demand nights declined across the continent.
 RUKAIYA KADIWAL
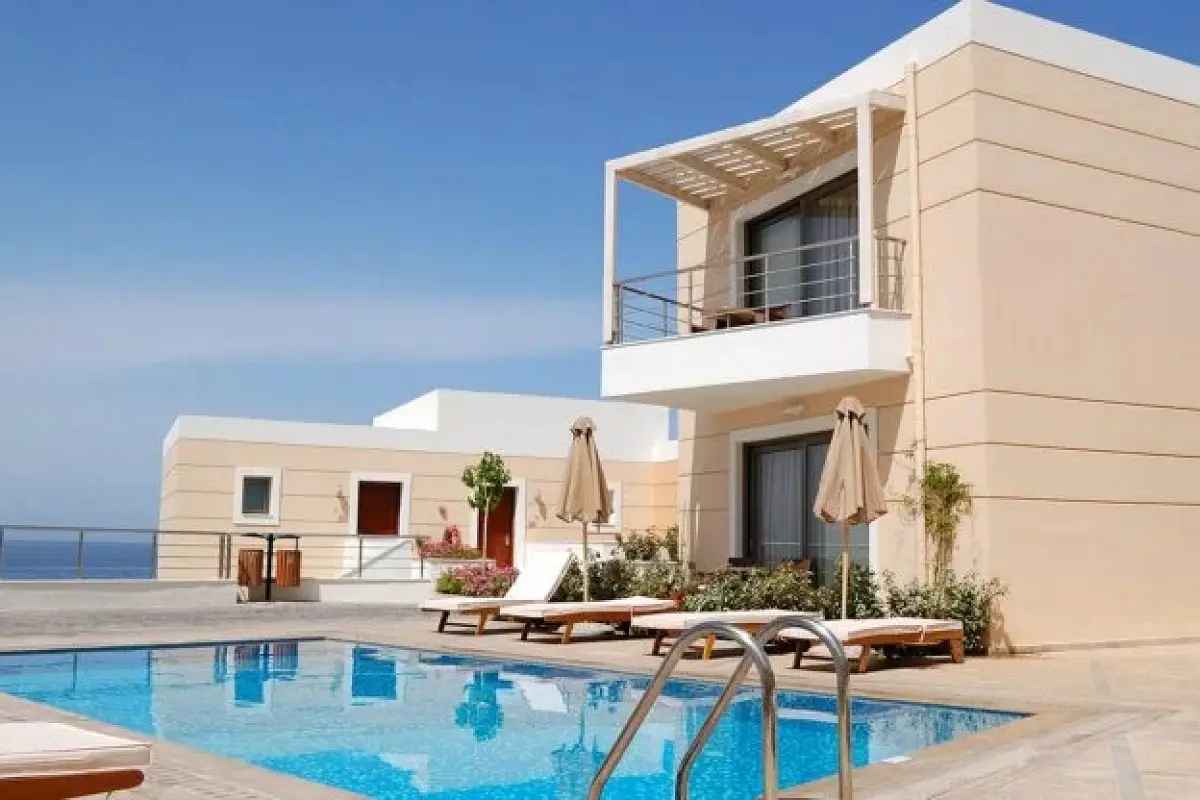
Sun lounges sit empty beside a private pool overlooking a hazy stretch of Mediterranean coastline, striped umbrellas closed against an afternoon breeze that has, for once, no one to shade. A single potted geranium leans against a whitewashed wall, the only sign that someone recently tended this villa before its most recent guests departed. Scenes like this one, quiet and half occupied, tell a subtler story than any single booking figure could, and that story now has a name attached to it, the Europe Short Term Rental Market.
Europe's short term rental market recorded 4.3% RevPAR growth in August as ADR increased 7.5%, while demand nights declined 3.1% and occupancy fell to 70.4%. According to AirDNA's new Monthly Review, the continent's rental sector recorded continued rate growth in August 2026, even as demand and occupancy moved in the opposite direction.
Rising Rates Against Falling Demand
RevPAR increased 4.3% to 113 euros, driven by a 7.5% rise in ADR to 160 euros, while occupancy fell 2.1 percentage points to 70.4%. That combination, higher prices paired with fewer nights booked, illustrates a market where hosts are successfully commanding stronger rates even as fewer travellers ultimately fill those available nights.
Supply increased 1.7% year over year, remaining within the narrow growth range recorded since spring, while demand nights declined 3.1%. The Repeat Rent Index increased 6.1%, indicating that rate growth was recorded among listings that remained active over time rather than simply reflecting new, higher priced inventory entering the market.
A Summer of Broadly Similar Trends
During the summer period from June to August, Europe's RevPAR increased 5.5% to 105 euros. ADR averaged 157 euros, up 7.8%, while occupancy declined 1.4 percentage points to 66.9%, confirming that August's individual monthly pattern reflected a broader seasonal trend rather than a single month's anomaly.
All of Europe's top 20 markets recorded year over year ADR growth in August and during the summer period, while RevPAR increased in 18 of 20 markets in August and in all 20 markets over the summer, a remarkably consistent pattern across a continent with otherwise wildly varying local rental dynamics.
Spain and Germany Driving the Demand Shortfall
Europe's demand decline was concentrated in two countries specifically. Summer demand nights totalled 174.9 million, down 2.0% year over year, with Spain accounting for 68.8% of the continent's 3.6 million night shortfall, while Germany contributed a further 30.5%. Excluding Spain, the summer decline was just 0.7%, and excluding both Spain and Germany, European demand was almost unchanged at negative 0.02%.
Spain's decline was associated with its regulatory delisting program, while Germany's decline reflected a domestic pullback from its own coast. Spain's demand declined 12.5% over the summer and 14.3% in August, while Croatia recorded a summer decline of 9.6%, marking these three markets as clear outliers against an otherwise more stable continental picture.
Where Demand Actually Grew
Other markets recorded genuine demand growth during the summer. Italy increased 0.8%, the UK increased 1.6%, Albania increased 19.7%, Sweden increased 7.8%, Poland increased 6.4%, and Norway increased 5.0%, while France declined 1.4%. Of Europe's 42 markets, 23 recorded summer demand growth and 19 recorded declines, suggesting the overall continental narrative masks considerable regional variation beneath the surface.
The strongest demand growth in Europe occurred along the eastern Adriatic coast specifically, with Albania increasing 19.7% and Montenegro increasing 17.6%, both markets located at approximately 41 to 42 degrees north latitude, a striking cluster of growth immediately adjacent to Croatia's own steep decline. Full details on the report are available on the official TravelDailyNews website.
Spain's Regulatory Delisting Reshapes Supply
Spain recorded the largest contraction in available listings in Europe during the summer, with supply declining 8.9% in August and 10.7% over the summer. The decline coincided with a regulatory delisting order issued around June to July 2025, with removals phased in over subsequent months rather than occurring simultaneously.
The decline extended well beyond Madrid and Barcelona, with approximately 75% of Spanish municipalities recording lower listings during the summer, while the country's largest cities collectively represented only around 10% of the total decrease. The listings that exited the market generally had lower rates and occupancy than those that remained, though the pattern covered most price segments rather than concentrating purely among the lowest priced properties.
Large Hosts Absorbed Most of the Demand Loss
Hosts managing 100 or more units controlled 17.3% of European demand but accounted for 79% of the summer demand decline. Their demand fell 8.7%, while supply was almost unchanged, declining just 0.6%, and their occupancy decreased 2.8 percentage points, compared with a 1.0 percentage point decline for single unit hosts.
Mid sized operators told a different story entirely. Hosts managing 6 to 20 units increased demand by 2.4%, while those managing 21 to 99 units increased demand by 1.4%, suggesting that smaller, more nimble operators weathered this particular downturn considerably better than large scale institutional portfolios.
Northern Markets Outperformed the South
Demand growth during the summer was notably higher in markets located at or above 55 degrees north latitude. These eight markets recorded a 5.2% increase in demand, compared with a 2.5% decline in areas below 55 degrees, with occupancy declining by only 0.78 percentage points in the northern markets, compared with 1.44 percentage points elsewhere.
Within that northern group, Sweden increased demand by 7.8%, Finland by 7.2%, Norway by 5.0%, and Denmark by 4.9%, a pattern suggesting shifting traveller preferences toward cooler climates during a summer marked by intense heat across much of southern Europe.
What This Data Reveals About Traveller Behaviour
Taken together, these figures paint a picture of a European rental market successfully raising prices even as fewer travellers book, a dynamic that ultimately favours smaller, well positioned hosts over sprawling institutional portfolios more exposed to shifting regional demand patterns. That kind of market recalibration, where value shifts toward operators with genuine local presence and flexibility, echoes broader concerns increasingly voiced across the hospitality and luxury travel sector regarding vulnerability, trust and operational resilience, themes also explored in recent coverage of how high profile security concerns are reshaping luxury hospitality across major European destinations.
A Quiet Pool, A Complicated Season
Back beside that empty pool overlooking the Mediterranean, the closed umbrellas and untouched lounge chairs capture something the raw percentages alone cannot, the lived reality of a market where higher nightly rates have not always translated into fuller calendars. Whether this pattern of rising prices and softening demand persists into the autumn booking season, already showing modest growth of 2.3% for September through December, will determine whether 2026 is remembered as a temporary correction or the beginning of a more lasting shift in how Europe's short term rental economy actually behaves.