Zenith Aviation Collapse Grounds Fleet, 41 Jobs Lost
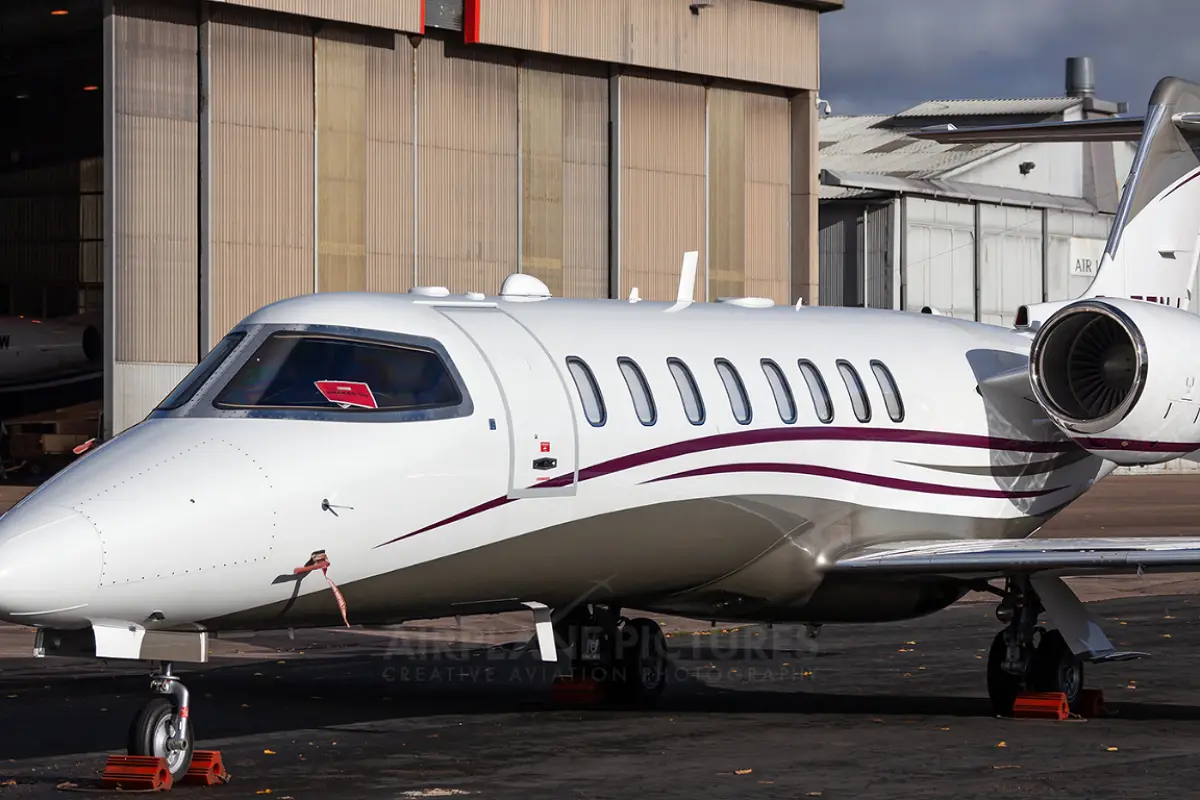
Zenith Aviation has entered administration at Biggin Hill Airport, leaving grounded Learjets, 41 job losses, and up to £5 million in debt.
 Jishan Khan
Zenith Aviation Has Collapsed, And the Way It Fell Apart Tells You Something Important About the Hidden Fragility Underneath Private Aviation's Glossy Image
Grounded Learjets at Biggin Hill. 41 jobs gone. Debts between £3 million and £5 million. And a UK Air Operator Certificate that is now one of the most valuable things left in the wreckage. This is what happens when the economics of small private aviation finally catch up with the ambition.
The private aviation industry in 2026 has a visibility problem, not the kind where nobody knows it exists, but the opposite kind. The G700 orders, the record charter demand, the billionaire clients, and the luxury positioning have created a public image of a sector that is thriving uniformly and without exception.
Zenith Aviation's collapse into administration at London Biggin Hill Airport is the corrective to that image.
The UK private jet operator has gone under after severe cash flow problems, unpaid debts, and internal management failures accumulated to a point where the business became unrescuable without outside intervention. Forty-one people have lost their jobs. The company's Learjet fleet is grounded. Administrators are now working through debts estimated somewhere between £3 million and £5 million while exploring whether a rescue or buyout can salvage anything from what remains.
The numbers are small by aviation industry standards. The story they tell is not.
The Gap Between Private Aviation's Headlines and Its Ground-Level Economics
The private aviation boom that accelerated through the post-pandemic period was real. Demand genuinely surged. Charter prices genuinely rose. High-net-worth clients genuinely shifted toward private travel in ways that looked structural rather than cyclical.
What the headlines about that boom consistently underreported was the distribution of those benefits across the sector. The operators who captured the upside of surging demand were predominantly the larger, better-capitalised companies, the ones with diverse fleets, strong broker relationships, robust maintenance infrastructure, and the financial reserves to handle the operational volatility that comes with managing aircraft at scale.
Smaller operators like Zenith, working with a Learjet fleet at a single base, serving a narrower client segment, and operating without the financial buffer that larger competitors carry, found themselves in a different position. Rising demand brought rising costs simultaneously — fuel, maintenance, crew wages, insurance, and regulatory compliance all became more expensive at the same time that client expectations rose and competition for the best charter brokers' attention intensified.
Cash flow in private aviation is structurally difficult for small operators in ways that are not immediately obvious from the outside. Aircraft are expensive to maintain and expensive to keep grounded. Charter revenue is lumpy and seasonal. The gap between when costs are incurred and when revenue is collected can be wide enough to create serious liquidity problems even in periods of reasonable trading activity.
Zenith's cash flow crisis did not require a catastrophic external event to trigger. It required the ordinary pressures of running a small private jet operation in an environment that has become progressively less forgiving for operators without scale.
Post-Brexit Regulatory Complexity Is a Real and Underreported Cost
The specific mention of post-Brexit regulatory complexity in the context of Zenith's difficulties is not incidental and deserves to be examined properly.
Before Brexit, UK-based private aviation operators could fly freely across European Union airspace and serve EU-based clients under a unified regulatory framework. The operational and commercial flexibility that came with full access to the European market was a fundamental part of the business model for operators like Zenith, particularly those with the kind of international charter client base that naturally generates flying across European destinations.
Post-Brexit, the regulatory landscape for UK Air Operator Certificate holders operating in Europe has become significantly more complex. Third-country operator permissions, bilateral aviation agreements that vary by country, and the administrative overhead of managing compliance across multiple regulatory jurisdictions have added costs and operational friction that simply did not exist before 2021.
For a large operator with a dedicated compliance and regulatory affairs team, these changes are manageable if expensive. For a small operator already running lean on administrative resource, they represent a material ongoing cost burden that compresses margins on exactly the cross-border European flying that was previously among the most profitable activity in the charter portfolio.
Zenith is unlikely to be the last UK private aviation operator for whom post-Brexit regulatory complexity contributed to a viability problem. It is simply the most recently visible example of a pressure that is quietly affecting the economics of the entire small and mid-size UK charter sector.
The UK Air Operator Certificate Is Now the Most Valuable Thing in the Wreckage
The detail that reveals most about how private aviation's economics actually work right now is the observation that Zenith's UK Air Operator Certificate, the regulatory authorisation that allows an organisation to conduct commercial air transport operations, has become one of the most strategically valuable assets in the administration.
Obtaining a UK AOC is a lengthy, expensive, and genuinely demanding process. Regulatory assessment, safety management system development, operations manual production, flight operations inspector oversight, and the organisational requirements that must be satisfied before the Civil Aviation Authority will issue the certificate represent a significant investment of time and money that can take years to complete.
For an operator looking to establish or expand UK private aviation operations quickly, acquiring an existing AOC through a distressed purchase is dramatically faster and potentially cheaper than building from scratch. The grounded Learjets and the operational infrastructure at Biggin Hill have value too, but the AOC is the asset that makes the whole package worth serious attention from potential acquirers.
This dynamic, where the regulatory permission to operate has become more valuable than the physical assets of a failed business, tells you something important about where the barriers to entry in UK private aviation currently sit. The regulatory environment has become demanding enough that existing authorisations carry genuine scarcity value, which in turn makes small operator failures an acquisition opportunity for better-capitalised competitors rather than simply a market exit.
Biggin Hill and What the Airport Loses
London Biggin Hill has built a specific identity as a business aviation hub serving the premium end of the London private jet market, a positioning that depends on maintaining a critical mass of high-quality operators based at the airport.
Zenith's collapse and the grounding of its Learjet fleet removes capacity from that ecosystem at a time when the airport is working to maintain and grow its premium business aviation positioning against competition from other London-area private jet facilities.
Forty-one job losses at a single operator is not an abstract statistic at an airport of Biggin Hill's size. It is a meaningful reduction in the skilled aviation workforce based there, pilots, engineers, operations staff, and ground handling personnel whose expertise and relationships are part of what makes the airport function as a serious business aviation centre rather than just a runway with facilities.
Whether the administrator can find a buyer who will reactivate the AOC, rehire some of the workforce, and restore operating capacity at Biggin Hill is the most practically important question in the short term, both for the individuals who lost their jobs and for the airport's broader operational health.
What the Private Jet Sector Needs to Acknowledge
Zenith's collapse is a prompt for the private aviation industry to have a more honest conversation about the structural health of its smaller operator segment than the dominant narrative of luxury demand and record charter prices typically allows.
The demand is real. The premium client growth is real. But the benefits of that growth are concentrating upward toward scale operators while the cost pressures are hitting smaller operators from multiple directions simultaneously, fuel, regulation, maintenance, crew costs, and the post-Brexit complexity that adds friction to the European flying that smaller UK operators depend on.
A sector that allows its smaller operators to fail at scale is a sector that is gradually consolidating toward a small number of large players, a structure that typically reduces competition, reduces choice for clients, and reduces the innovation that comes from a diverse ecosystem of operators approaching the market from different angles.
Zenith Aviation is one company with 41 employees and a Learjet fleet at Biggin Hill. But what it represents is a fragility that sits beneath private aviation's polished surface and that the industry's most prominent voices have not yet adequately acknowledged or addressed.
The administrators are looking for a buyer. The sector should be looking for a reckoning.